
If a company offers you 11.5 LPA, the first calculation that probably comes to mind is simple:
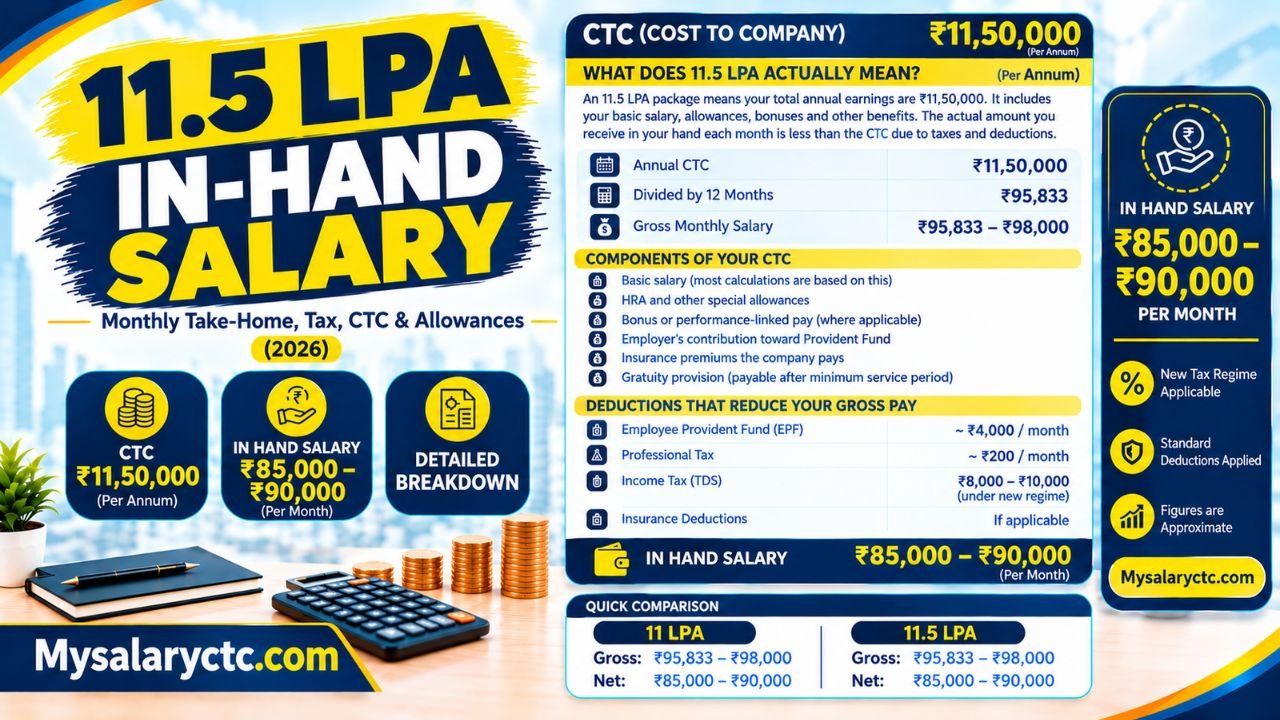
₹11,50,000 ÷ 12 = ₹95,833 per month.
But there is a catch.
₹95,833 is the monthly equivalent of the CTC—not necessarily the amount you will receive in your bank account.
Your actual 11.5 LPA in hand salary depends on how the employer has built your compensation package. Basic salary, employer PF, gratuity, variable pay, professional tax, income tax and other deductions can all change the final amount.
Current online salary models for an ₹11.5 lakh package show materially different outcomes. One model estimates around ₹81,829 per month, while other calculators show ranges reaching approximately ₹89,720–₹92,233 depending on their assumptions. This difference is not necessarily an error; it demonstrates how strongly the salary structure affects take-home pay. [Reference Source: SalaryInHand, GreyHR, Jupiter Money]
This guide explains 11.5 LPA in hand salary per month from the perspective that actually matters to an employee: How much can I expect to receive, what gets deducted, and what should I check before accepting the offer?
11.5 LPA In Hand Salary Per Month: Quick Answer
An 11.5 LPA CTC means your annual Cost to Company is:
₹11,50,000 per year
Dividing that by 12 gives:
₹95,833 per month
However, your actual monthly bank credit can be lower because CTC may include employer-side contributions, gratuity, insurance, variable compensation and other benefits.
Current published calculators illustrate a wide range:
| 11.5 LPA salary calculation | Approximate monthly figure |
| Monthly CTC equivalent | ₹95,833 |
| Lower illustrative take-home | Around ₹79,300 |
| One detailed salary model | ₹81,829 |
| Higher illustrative range | Around ₹87,100–₹92,233 |
| Actual employee take-home | Depends on the offer structure |
[Reference Source: SalaryInHand, Jupiter Money, GreyHR]
Therefore, there is no single universal answer to the question “What is the 11.5 LPA in hand salary?”
Your offer letter is the deciding document.
What Does 11.5 LPA Actually Mean?
Before calculating take-home pay, it is important to understand the three salary numbers that employees often confuse.
CTC
CTC means Cost to Company.
It represents the overall annual cost associated with employing you. Depending on the employer, it can include salary plus employer contributions, gratuity, insurance, bonuses and other benefits.
Gross Salary
Gross salary is the amount considered before employee-side deductions such as PF and applicable taxes.
In-Hand Salary
In-hand salary, also called take-home salary or net salary, is the amount that actually reaches your bank account after applicable deductions.
The relationship can be simplified as:
CTC → Gross Pay → Employee Deductions → Bank Credit
That is why an employee with an 11.5 LPA CTC should not automatically expect ₹95,833 every month.
For example, one current 11.5 LPA model starts with ₹11.5 lakh CTC but arrives at ₹87,779 gross monthly pay and ₹81,829 monthly take-home, after accounting for employer PF, gratuity, employee PF and professional tax under its assumptions. [Reference Source: SalaryInHand]
Understanding an 11.5 LPA Salary Structure
The most useful way to understand your package is to stop looking at the CTC as one big number.
Instead, imagine the ₹11.5 lakh being divided into several buckets.
A hypothetical structure could look like this:
| Component | Illustrative annual amount |
| Basic salary | ₹5,75,000 |
| HRA | ₹2,87,500 |
| Special allowance | ₹1,90,842 |
| Employer PF | ₹69,000 |
| Gratuity | ₹27,658 |
| Total CTC | ₹11,50,000 |
This particular structure is based on a published salary model and should be treated as an illustration, not a standard Indian salary template. [Reference Source: SalaryInHand]
Notice what happens here.
The employee does not receive every component as monthly cash.
Employer PF and gratuity may form part of CTC without appearing as spendable monthly income. This is one of the main reasons the headline package and bank credit can look surprisingly different.
The Four Numbers You Should Find in Your Offer Letter
If you’re considering an 11.5 LPA job, look for these four figures before making your decision.
1. Total CTC
This should say something close to:
₹11,50,000 per annum
But don’t stop there.
2. Fixed CTC
This tells you how much compensation is relatively predictable.
A package with ₹10.8 lakh fixed and ₹70,000 variable is very different from an 11.5 LPA package containing ₹2 lakh of performance-linked pay.
3. Variable Pay
Variable compensation may depend on individual performance, company performance, targets or other conditions.
If your offer includes a large variable component, ask HR:
- Is it guaranteed?
- How frequently is it paid?
- What percentage did employees actually receive last year?
- Is it included in monthly salary?
- Is it paid annually?
4. Monthly Gross
This is particularly useful for estimating your actual bank credit.
If HR gives you the expected gross monthly salary, the calculation becomes much easier.
How PF Changes Your 11.5 LPA Take-Home Salary
Provident Fund can be one of the most important components affecting your monthly salary.
EPFO’s published guidance states that employee PF contribution is generally 12% of applicable wages, while contribution arrangements and wage ceilings can affect how PF is calculated. The official EPFO material also explains that contributions on higher wages can operate under specific conditions. [Reference Source: Employees’ Provident Fund Organisation]
So you should not calculate PF simply as:
12% of ₹11,50,000
That would be the wrong approach in many salary structures.
PF is generally connected to the applicable PF wages/basic component rather than simply being 12% of total CTC.
Example
Suppose an employer uses a basic salary of ₹47,917 per month.
A simplified 12% calculation would be:
₹47,917 × 12% ≈ ₹5,750
That would mean approximately ₹5,750 could be deducted from the employee’s monthly salary under that particular structure.
Over a year:
₹5,750 × 12 = ₹69,000
The published 11.5 LPA example from SalaryInHand uses exactly this kind of structure, with ₹69,000 shown as annual employee PF. [Reference Source: SalaryInHand]
But your actual PF deduction may be different.
This is why basic salary matters when calculating take-home pay
Does an 11.5 LPA Salary Have Income Tax?
This is where many online salary articles become confusing.
Tax is not calculated simply by taking 11.5 lakh and applying one percentage to the entire amount.
For the applicable tax year, taxable income and the selected tax regime matter.
For AY 2026–27, the Income Tax Department lists the new-regime slabs as:
- Up to ₹4 lakh — Nil
- ₹4 lakh to ₹8 lakh — 5%
- ₹8 lakh to ₹12 lakh — 10%
- ₹12 lakh to ₹16 lakh — 15%
- ₹16 lakh to ₹20 lakh — 20%
- ₹20 lakh to ₹24 lakh — 25%
- Above ₹24 lakh — 30%
The department also states that eligible resident individuals can receive a Section 87A rebate of up to ₹60,000 when total income falls within the specified ₹12 lakh threshold under the new regime. A 4% health and education cess applies to income tax plus surcharge, where applicable. [Reference Source: Income Tax Department]
This is particularly relevant to an 11.5 LPA salary.
A salary model may arrive at zero income tax under its new-regime assumptions, because taxable income can be below the relevant rebate threshold after the applicable deductions. One current 11.5 LPA example reports taxable income of ₹9,78,342 and zero income tax under its assumptions. [Reference Source: SalaryInHand]
However, don’t copy that result blindly.
Your taxable income may differ depending on:
- Salary structure
- Taxable allowances
- Other income
- Capital gains
- Employer benefits
- Applicable tax year
- Tax regime
- Other taxable components
Therefore, “11.5 LPA means zero tax” should not be treated as a universal rule.
The correct statement is:
An employee with an 11.5 LPA package may have little or no income-tax liability under certain new-regime circumstances, but the final tax calculation depends on the individual’s taxable income.
Read More: 10 LPA In Hand Salary in India 2026: Monthly Take-Home, CTC Breakdown, PF, Tax & Salary Calculation
11.5 LPA In Hand Salary: Step-by-Step Calculation
Let’s build the calculation from scratch.
Step 1: Start With Annual CTC
₹11,50,000
This is the employer’s stated annual package.
Step 2: Remove CTC Components That Aren’t Monthly Cash
Depending on the employer, this could include:
- Employer PF
- Gratuity
- Insurance
- Annual bonus
- Other benefits
Suppose an illustrative structure has ₹96,658 of annual components that are not part of regular monthly pay.
That leaves:
₹11,50,000 − ₹96,658 = ₹10,53,342
This is approximately the annual gross-pay pool under that particular model.
Step 3: Convert Gross to Monthly Amount
₹10,53,342 ÷ 12
≈ ₹87,779 per month
Step 4: Deduct Employee PF
Suppose employee PF is:
₹69,000 per year
or:
₹5,750 per month
Step 5: Consider Professional Tax
Professional tax depends on the applicable state and payroll structure.
One published 11.5 LPA example uses ₹2,400 annually. [Reference Source: SalaryInHand]
Step 6: Account for Income Tax
Under the particular assumptions used by that model, income tax is ₹0 under the new regime.
Step 7: Arrive at Take-Home
Using that example:
₹87,779 − ₹5,750 − ₹200 = ₹81,829
So the model arrives at:
₹81,829 monthly in hand
Again, this is an illustrative calculation, not a guaranteed salary figure. [Reference Source: SalaryInHand]
Why Different Websites Give Different 11.5 LPA Figures
This is one of the most important things to understand when researching salary online.
You may find:
- ₹81,829 on one website
- ₹79,300–₹87,100 on another
- ₹89,720–₹92,233 on another calculator
That doesn’t automatically mean one website is wrong.
They may be using different assumptions.
For example, GreyHR currently lists an estimated ₹89,720–₹92,233 monthly range for 11.5 LPA, while Jupiter Money lists ₹79,300–₹87,100. [Reference Source: GreyHR; Jupiter Money]
The difference can come from:
Different Basic Salary
A 40% basic and a 50% basic can produce different PF deductions.
Different CTC Treatment
One employer may include gratuity in CTC while another may not.
Different Variable Pay
A bonus included in CTC may not appear in regular monthly salary.
Different PF Assumptions
PF can significantly alter the take-home amount.
Different Tax Assumptions
Tax regime and taxable income can change the result.
Different Professional Tax
Professional tax is state-specific.
Therefore, online calculators should be treated as planning tools, not official salary slips.
Real-World Example: Two Employees, Same 11.5 LPA CTC
Consider two fictional employees.
Employee A
Annual CTC: ₹11.5 lakh
- Fixed compensation: high
- Variable pay: low
- Employer PF included
- Moderate basic salary
- Standard deductions
Their monthly bank credit could be toward the higher end of an estimated take-home range.
Employee B
Annual CTC: ₹11.5 lakh
- Fixed compensation: lower
- Variable pay: ₹1.5 lakh
- Higher basic salary
- Employer PF included
- Gratuity included in CTC
Employee B could have a noticeably lower regular monthly credit even though both employees can say:
“I earn 11.5 LPA.”
That is why experienced job seekers don’t compare offers by CTC alone.
They compare:
Fixed pay + monthly gross + variable pay + deductions + benefits.
What Can You Afford With an 11.5 LPA Salary?
Suppose your actual take-home is approximately ₹82,000 per month.
A practical monthly plan could look something like:
| Category | Illustrative budget |
| Rent | ₹18,000 |
| Food & groceries | ₹8,000 |
| Transport | ₹5,000 |
| Utilities & phone | ₹3,000 |
| Personal spending | ₹5,000 |
| Family support | ₹10,000 |
| Investments | ₹20,000 |
| Emergency buffer | ₹5,000 |
| Remaining amount | ₹8,000 |
This is not a recommended universal budget.
Your expenses will depend heavily on your city, rent, family responsibilities, lifestyle and financial goals.
The bigger lesson is that take-home salary is more useful than CTC when creating a monthly budget.
If you’re moving from a lower salary to 11.5 LPA, avoid increasing every expense immediately. A salary jump can create a much stronger financial position when part of the additional income is directed toward emergency savings and long-term investments.
How to Evaluate an 11.5 LPA Job Offer
Before accepting the offer, ask HR for a detailed compensation sheet.
You can use this checklist:
Compensation checklist
- Total CTC
- Fixed CTC
- Variable CTC
- Monthly gross
- Basic salary
- HRA
- Employee PF
- Employer PF
- Gratuity
- Insurance
- Professional tax
- Expected TDS
- Joining bonus
- Retention bonus
- Performance bonus
- Notice period
- Appraisal cycle
The most important question is:
“What will be my approximate monthly take-home after employee-side deductions?”
Getting this number from HR before joining can prevent unpleasant surprises after your first payslip.
Read More: 11 LPA In Hand Salary in India: How Much Will You Actually Get Every Month?
Common Mistakes When Calculating 11.5 LPA In-Hand Salary
Mistake 1: Treating ₹95,833 as take-home
It is simply the monthly CTC equivalent.
Mistake 2: Calculating PF on total CTC
PF is not simply 12% of ₹11.5 lakh. Applicable PF wages and the employer’s structure matter. [Reference Source: EPFO]
Mistake 3: Ignoring variable compensation
A performance-linked ₹1 lakh is not the same as ₹1 lakh of guaranteed fixed salary.
Mistake 4: Assuming every calculator is using your salary structure
Online calculators use assumptions.
Mistake 5: Looking only at tax
PF, gratuity, professional tax, insurance and variable pay can also affect the difference between CTC and monthly cash.
Mistake 6: Comparing two offers only by LPA
An 11.5 LPA package with high fixed pay can be structured very differently from another 11.5 LPA package with substantial variable compensation.
Future of Salary Structures in India
Salary structures are becoming more transparent in some organizations, but compensation is also becoming more complex as companies combine fixed salary, performance incentives, benefits and flexible compensation.
For employees, this makes salary literacy increasingly important.
Instead of asking only, “What is the package?”, candidates should understand the relationship between CTC, fixed compensation, gross salary and net pay.
Tax rules, payroll practices and employment benefits can also change over time, so salary calculations should always be checked against the rules applicable to the relevant financial year. [Reference Source: Income Tax Department; EPFO]
Frequently Asked Questions About 11.5 LPA In Hand Salary
There is no single fixed amount. Current online calculators show different estimates, with examples ranging from roughly ₹79,000 to ₹92,000 per month, depending on salary structure and assumptions. One detailed model gives ₹81,829 per month. [Reference Source: SalaryInHand, GreyHR, Jupiter Money]
₹11,50,000 divided by 12 equals approximately:
₹95,833 per month
But this is the monthly CTC equivalent, not necessarily your bank credit.
Whether an 11.5 LPA salary works well depends on your location, experience, household expenses, financial commitments and the structure of the offer. A package should be evaluated through its fixed pay and take-home amount rather than CTC alone.
There is no universal deduction. It depends on the applicable PF wage and employer structure. EPFO’s published framework specifies a standard employee contribution rate of 12% under the applicable rules. [Reference Source: EPFO]
It can depend on your taxable income and tax regime. Under the AY 2026–27 new regime, the Income Tax Department provides a Section 87A rebate for eligible resident individuals whose total income is within the specified threshold. [Reference Source: Income Tax Department]
Your CTC may include employer PF, gratuity, insurance, variable compensation and other components that aren’t paid to you as regular monthly cash. Employee-side deductions can reduce the amount further.
Yes. Their basic salary, PF arrangement, variable pay, benefits, tax situation and other payroll deductions can differ.
Ask for the complete salary breakup, including fixed CTC, variable pay, basic salary, monthly gross, employee PF, employer PF, gratuity, insurance, expected TDS and estimated monthly in-hand salary.
Final Takeaway: What Is the Real 11.5 LPA In Hand Salary?
An 11.5 LPA CTC equals ₹11,50,000 annually, or approximately ₹95,833 per month when simply divided by 12.
But that calculation does not tell you what will reach your bank account.
Current salary calculators produce noticeably different estimates because they use different assumptions. A detailed current example calculates ₹81,829 monthly, while other published calculators place 11.5 LPA in a broader range. [Reference Source: SalaryInHand, GreyHR, Jupiter Money]
The smartest way to calculate your personal 11.5 LPA in hand salary per month is therefore to start with your actual offer letter.
Look at the:
CTC → Fixed Pay → Basic → Employer PF → Gratuity → Variable Pay → Employee PF → Tax → Final Bank Credit
Once you understand those numbers, the headline 11.5 LPA becomes much more meaningful.
Before accepting an offer, always ask for the complete compensation breakup and expected monthly take-home. Your payslip—not the headline CTC—is the number that determines your monthly cash flow.
Read Our Tools: CTC Calculator | Download Salary Slip | Salary Tax Calculator

Hi, I’m Kashish Arora, an SEO specialist and finance content researcher passionate about simplifying salary and compensation topics. I create well-researched content on CTC, in-hand salary, salary structure, pay scales, salary slips, tax calculations, EPF, gratuity, bonuses, deductions, and employee benefits.
My articles are based on official government guidelines, employer policies, tax regulations, and other reliable public sources. I aim to explain complex payroll and taxation concepts in simple language so that employees, job seekers, HR professionals, and students can easily understand how salaries are calculated and how deductions affect take-home pay.
Along with payroll and taxation topics, I also cover salary insights for government employees, private-sector professionals, executives, and public personalities whenever reliable information is available.
Leave a Reply