
Seeing ₹9.5 LPA on a job offer can be exciting. But before you calculate your monthly budget, there is one important question to answer:
How much of that ₹9.5 lakh will actually reach your bank account?
If you divide ₹9,50,000 by 12, you get approximately ₹79,167 per month. However, this is only the monthly equivalent of the annual package. It does not necessarily represent your take-home salary.
A company’s CTC may contain employer PF, gratuity, insurance, incentives, bonuses and other components that aren’t paid to you as regular monthly cash. Your own deductions can also include employee PF, professional tax and, where applicable, tax deducted at source.
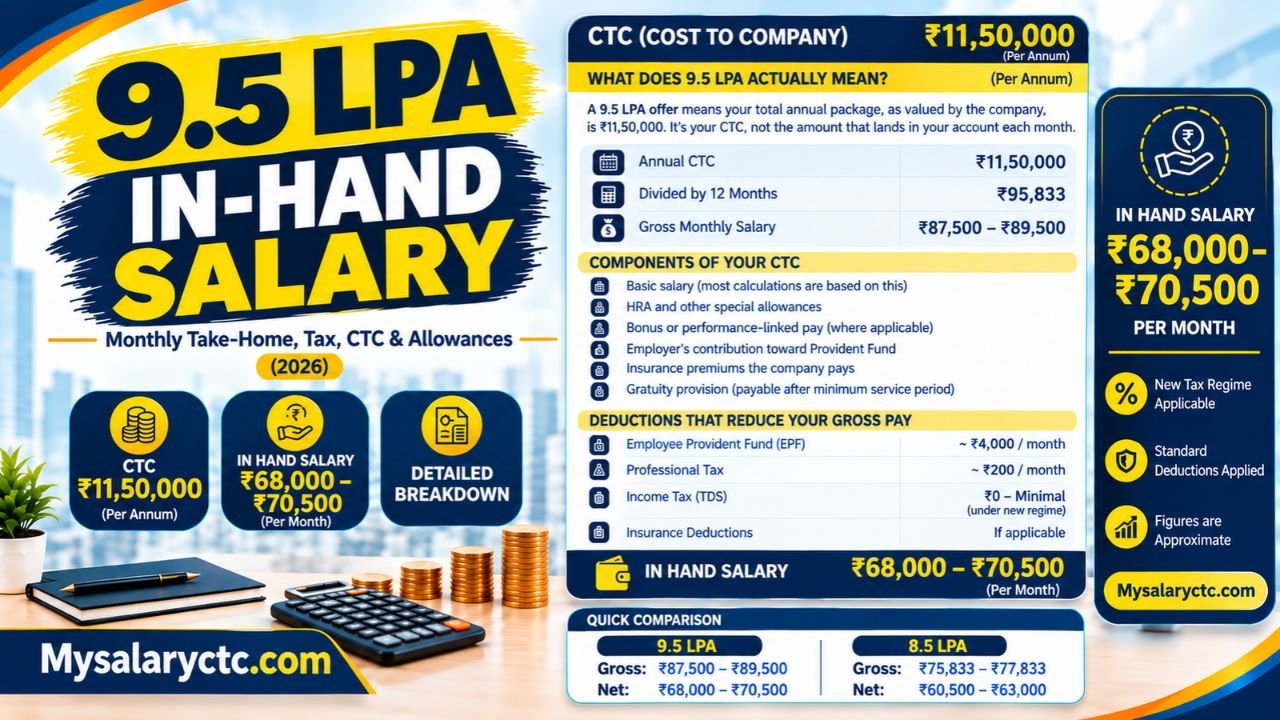
Current salary calculators illustrate the difference. Depending on the assumptions used, published calculations for a ₹9.5 lakh CTC produce monthly take-home figures ranging from roughly ₹67,500 to ₹75,500.
So, if you searched for “9.5 LPA in hand salary” or “9.5 LPA in hand salary per month,” this guide will help you understand the number behind the package instead of relying on a single generic calculator.
Quick Answer: 9.5 LPA In Hand Salary Per Month
A ₹9.5 LPA package equals:
₹9,50,000 ÷ 12 = ₹79,167 per month
But ₹79,167 is the monthly CTC equivalent, not necessarily your bank credit.
Under different salary structures, current published examples show approximately:
| Calculation Model | Approx. Monthly Take-Home |
| Lower illustrative structure | ₹67,500+ |
| Example with 50% basic | ₹67,563 |
| Example with 40% basic | ₹71,367 |
| Mid-range calculator estimate | ₹73,454 |
| Higher illustrative structure | ₹75,500+ |
These are examples rather than guaranteed salaries. The exact amount depends on your employer’s breakup, PF treatment, variable compensation, state-specific deductions and tax circumstances.
Understanding a ₹9.5 Lakh Salary Package
Before calculating take-home pay, it helps to understand what the phrase 9.5 LPA actually represents.
LPA means “Lakhs Per Annum”
So:
9.5 LPA = ₹9.5 lakh per year = ₹9,50,000 annually
If the entire amount were paid as straightforward monthly salary with no employer-side components or deductions:
₹9,50,000 / 12 = ₹79,166.67
But employment compensation usually isn’t that simple.
A CTC can have several layers.
Think of your salary as three separate numbers
CTC → Gross Pay → Net Pay
For example:
CTC: ₹9,50,000
↓
Gross salary: Amount actually structured as salary before employee deductions
↓
Net/in-hand salary: Amount remaining after applicable deductions
This distinction is why searching for a single universal 9.5 LPA in hand salary per month figure can be misleading.
Why Your ₹9.5 LPA Package Doesn’t Equal ₹79,167 Cash
Imagine two companies offer the following:
Offer A
Total CTC: ₹9.5 lakh
- Fixed salary: ₹8.9 lakh
- Variable pay: ₹20,000
- Employer contributions/benefits: ₹40,000
Offer B
Total CTC: ₹9.5 lakh
- Fixed salary: ₹7.8 lakh
- Variable pay: ₹1 lakh
- Employer contributions/benefits: ₹70,000
Both employers can advertise the position as:
₹9.5 LPA CTC
Yet the employee receiving Offer A could have a different regular monthly salary from the employee receiving Offer B.
This is the key lesson:
The package number tells you the size of the compensation plan. The salary breakup tells you how much cash you receive.
What Can Be Included Inside 9.5 LPA CTC?
There isn’t one mandatory format that every employer follows.
Depending on the company, your compensation sheet could contain:
- Basic salary
- HRA
- Special allowance
- Flexible allowance
- Employer PF
- Gratuity
- Medical insurance
- Performance bonus
- Annual incentive
- Joining bonus
- Retention benefits
- Other employer-paid benefits
Some of these may be paid monthly, while others may be paid annually or only when specific conditions are met.
[Reference Source: Employer offer letter / compensation policy]
Therefore, when comparing job offers, don’t compare only:
₹9.5 LPA vs ₹9 LPA
Also compare:
Fixed pay + variable pay + benefits + expected monthly net salary
How to Work Out Your 9.5 LPA In Hand Salary
Instead of starting with tax, start with the compensation structure.
Step 1: Start With Annual CTC
Your headline number is:
₹9,50,000
The monthly CTC equivalent is:
₹79,167
This is your starting point—not your final salary.
Step 2: Remove Components That Aren’t Monthly Cash
Suppose your employer includes:
- Employer PF
- Gratuity
- Annual bonus
- Insurance
inside the ₹9.5 lakh package.
Those amounts should not automatically be treated as monthly cash salary.
For example, if ₹50,000 of the CTC represents employer-side contributions, that ₹50,000 isn’t simply another ₹4,167 deposited into your account every month.
The actual treatment depends on the employer’s payroll structure.
Step 3: Find the Monthly Gross
Once CTC-only components are separated, you can identify the amount classified as gross salary.
This is the number from which employee-side deductions are generally considered.
Step 4: Account for Employee PF
EPFO’s published contribution schedule lists the standard employee EPF contribution as 12%, with specific provisions and wage rules that affect how contributions are calculated. EPFO also notes a statutory wage ceiling of ₹15,000 for contributions under the standard framework, while higher-wage contributions can occur under specified arrangements.
That means you should not automatically calculate 12% of ₹9.5 lakh.
The actual PF deduction depends on the applicable PF wage and your employer’s arrangement.
For example, if the applicable PF wage were ₹30,000:
₹30,000 × 12% = ₹3,600
That would be an illustrative monthly employee PF contribution.
Your actual payslip may show a different amount.
Employee PF vs Employer PF
This is one of the easiest salary concepts to misunderstand.
Employee PF
This amount is deducted from your salary.
Therefore, it can reduce your monthly bank credit.
Employer PF
This is contributed by the company and may be counted inside CTC.
It represents part of your compensation package but isn’t normally paid to you as monthly spendable cash.
So an offer may effectively look like:
₹9.5 lakh CTC
but part of that amount may be going toward employer-side contributions.
EPFO’s published contribution schedule provides the statutory contribution framework and distinguishes employee and employer contributions.
Check This Also: 7 LPA In Hand Salary in India 2026: How Much Will You Actually Get Every Month?
What About Income Tax on 9.5 LPA?
This is where many salary articles oversimplify the calculation.
Income tax isn’t calculated simply by taking a fixed percentage of your CTC.
Your tax calculation depends on taxable income, applicable deductions/rebates and the tax regime.
The Income Tax Department’s official information for AY 2026–27 lists the new-regime slabs as:
| Taxable Income | Rate |
| Up to ₹4 lakh | Nil |
| ₹4–8 lakh | 5% |
| ₹8–12 lakh | 10% |
| ₹12–16 lakh | 15% |
| ₹16–20 lakh | 20% |
| ₹20–24 lakh | 25% |
| Above ₹24 lakh | 30% |
The Department also states that eligible resident individuals can receive a Section 87A rebate of up to ₹60,000 when taxable income does not exceed ₹12 lakh under the new regime.
For salaried taxpayers, the new-regime standard deduction is ₹75,000, according to the Income Tax Department’s current filing rules.
Important distinction
Don’t write:
“Everyone earning ₹9.5 LPA pays zero tax.”
A more accurate statement is:
A straightforward salaried taxpayer at this income level may have no final income-tax liability under the applicable new-regime provisions, but the result depends on taxable income and individual circumstances.
The Income Tax Department itself provides calculators that account for salary, other income, deductions and the selected tax regime.
A Fresh Example: Building a ₹9.5 LPA Salary
Let’s use a hypothetical salary structure rather than copying the standard examples used by other salary websites.
Assume an employer designs the package this way:
| Component | Annual Amount |
| Basic salary | ₹3,60,000 |
| HRA | ₹1,80,000 |
| Flexible/special allowance | ₹2,85,000 |
| Employer PF | ₹43,200 |
| Other CTC benefits | ₹81,800 |
| Total CTC | ₹9,50,000 |
Again, this is an educational illustration, not a universal salary structure.
The important thing to notice is that:
₹3,60,000 + ₹1,80,000 + ₹2,85,000
is not the same thing as the entire ₹9.5 lakh package.
Employer-side components account for the remaining portion.
What Could Your Monthly Bank Credit Look Like?
Suppose the monthly gross payable salary under a particular employer structure works out to approximately ₹75,000.
Then imagine the employee has:
- Employee PF: ₹3,600
- Professional Tax: state-dependent
- TDS: dependent on tax calculation
- Other deductions: ₹0
The employee’s bank credit would be below ₹75,000.
The precise result could therefore land in the high-₹60,000s or ₹70,000s depending on the structure.
This aligns with current published examples, which show different results for the same ₹9.5 lakh headline package. One model calculates ₹71,367 monthly, while another uses a different structure and arrives at ₹67,563.
Why Different Salary Calculators Give Different Answers
If you enter ₹9.5 LPA into multiple websites, you may notice that they don’t all show the same number.
That’s not necessarily an error.
They may be assuming different:
Basic salary percentage
One calculator might use 40%.
Another might use 50%.
PF treatment
One employer may use a PF ceiling structure.
Another may calculate contributions on higher eligible wages.
Gratuity
Some CTC structures include gratuity.
Others may present it separately.
Professional Tax
The applicable amount can depend on the state.
Variable compensation
One calculation may assume everything is fixed, while another excludes variable pay from regular monthly income.
Current published ₹9.5 LPA calculations demonstrate this variation directly.
9.5 LPA In Hand Salary: Three Different Situations
Situation 1: Mostly Fixed Compensation
Suppose almost the entire package consists of fixed salary, with only a small amount allocated to benefits or variable compensation.
Your monthly take-home may sit toward the higher end of the range.
Illustrative planning figure: ₹72,000–₹75,500/month
Situation 2: Employer PF and Other Benefits Included
Now imagine the employer includes PF and other CTC components inside the ₹9.5 lakh.
Your spendable monthly salary can be lower.
A current published example using its own assumptions estimates ₹67,563/month.
Situation 3: Large Variable Component
Suppose your offer says:
₹9.5 LPA CTC
but the structure is:
- Fixed: ₹8 lakh
- Variable: ₹1.5 lakh
Your monthly salary should not be calculated by simply dividing ₹9.5 lakh by 12.
The variable component might be paid quarterly, annually or according to performance conditions.
[Reference Source: Employer offer letter]
9.5 LPA Salary: Fixed vs Variable Pay
This is particularly important for job seekers changing companies.
Consider these two offers:
Company X
₹9.5 LPA
- Fixed: ₹9 lakh
- Variable: ₹50,000
Company Y
₹9.5 LPA
- Fixed: ₹7.5 lakh
- Variable: ₹2 lakh
The advertised CTC is identical.
But the guaranteed portion is not.
If your priority is monthly cash flow, the fixed component deserves close attention.
If your priority is total compensation, you may also want to understand how the variable component is calculated and what percentage has historically been paid.
[Reference Source: Employer compensation policy / offer letter]
What Is a Realistic 9.5 LPA In Hand Salary Per Month?
Based on current published calculation models:
- One example shows ₹67,563/month.
- Another shows ₹71,367/month.
- A broader calculator gives a range of approximately ₹67,554–₹75,358/month, depending on assumptions.
Therefore, rather than presenting one number as universally correct, it is more responsible to use:
Approximately ₹67,500–₹75,500 per month
as an illustrative planning range for a ₹9.5 LPA CTC.
Your actual salary could differ.
The offer letter is more authoritative than a generic internet calculator.
Check This Also: 8.5 LPA In Hand Salary in India 2026: Monthly Take-Home, CTC Breakdown & Tax Calculation
How to Calculate Your Exact Take-Home From an Offer Letter
Here’s a simple method you can use whenever you receive a salary offer.
First, write down:
Annual CTC = ₹9,50,000
Then identify:
Fixed CTC = ₹_____
Variable CTC = ₹_____
Employer PF = ₹_____
Gratuity = ₹_____
Insurance/benefits = ₹_____
Then find:
Monthly Gross = ₹_____
Now check the deductions:
Employee PF = ₹_____
Professional Tax = ₹_____
TDS = ₹_____
Other deductions = ₹_____
Finally:
Monthly In-Hand
Monthly Gross − Employee Deductions = Expected Bank Credit
This approach is much more useful than simply searching for a salary calculator result.
What Does a ₹9.5 LPA Salary Look Like on a Payslip?
A simplified monthly payslip could contain two sections.
Earnings
- Basic
- HRA
- Special Allowance
- Other Allowances
Deductions
- Employee PF
- Professional Tax
- TDS
- Other applicable deductions
The amount at the bottom marked Net Pay is the figure you should use for your monthly budgeting.
Your CTC isn’t the same as this net-pay figure.
Common Problems When Estimating 9.5 LPA Take-Home
Problem 1: Looking Only at CTC
Solution: Ask for the complete compensation breakup.
Problem 2: Assuming ₹79,167 Is Your Salary
Solution: Treat it as monthly CTC equivalent.
Problem 3: Applying 12% PF to ₹9.5 Lakh
Solution: Check the actual PF-applicable wage and employer structure.
Problem 4: Ignoring Variable Pay
Solution: Separate fixed and performance-linked compensation.
Problem 5: Using One Online Calculator as the Final Answer
Solution: Compare the calculator’s assumptions with your offer letter.
Problem 6: Confusing Tax Slabs With Final Tax
Solution: Calculate taxable income and applicable rebate rather than applying a slab percentage to the whole package.
A Better Way to Compare Two Job Offers
Suppose you’re choosing between:
Offer A — ₹9.5 LPA
and
Offer B — ₹10 LPA
Don’t immediately assume Offer B gives you ₹50,000 more annually in usable cash.
Instead create this comparison:
| Factor | Offer A | Offer B |
| Total CTC | ₹9.5 LPA | ₹10 LPA |
| Fixed CTC | — | — |
| Variable Pay | — | — |
| Monthly Gross | — | — |
| Employee PF | — | — |
| Professional Tax | — | — |
| Expected Net Pay | — | — |
| Employer Benefits | — | — |
Once these numbers are filled in, you can compare the offers on the basis of actual compensation rather than headline CTC.
Questions to Ask HR Before Joining
If your offer says ₹9.5 LPA, ask HR:
- What is my fixed annual compensation?
- How much is variable?
- Is employer PF included in CTC?
- Is gratuity included?
- What is my monthly gross salary?
- What will be deducted as employee PF?
- Is professional tax applicable?
- What is the expected monthly net salary?
- When is variable pay paid?
- Are there any joining or retention conditions?
A particularly useful question is:
“Could you please confirm the expected monthly net salary after standard employee-side deductions?”
This gives you a much clearer picture of your actual cash flow.
Future of Salary Calculations in India
Salary comparison is gradually becoming more detailed than simply comparing annual CTC figures.
Employees increasingly need to understand the difference between fixed compensation, variable compensation, employer contributions and net monthly pay.
The Income Tax Department now provides online tools capable of estimating tax under different regimes and taking salary and other income into account.
That makes personalized salary calculation more useful than relying on a single generic “in-hand salary” number.
FAQs: 9.5 LPA In Hand Salary
Depending on the salary structure, current published examples put monthly take-home around ₹67,500–₹75,500. This is an illustrative range rather than a guaranteed amount.
Depending on the salary structure, current published examples put monthly take-home around ₹67,500–₹75,500. This is an illustrative range rather than a guaranteed amount.
₹9.5 lakh divided by 12 equals approximately ₹79,167 per month. This is the monthly CTC equivalent.
Not necessarily. CTC may include employer contributions, benefits and variable compensation, while employee deductions can reduce monthly net pay.
There is no universal amount. The applicable PF wage and employer arrangement determine the actual contribution. EPFO lists 12% as the standard employee contribution rate under its published contribution schedule, subject to the applicable rules.
Tax depends on taxable income, applicable regime and individual circumstances. Under the AY 2026–27 new regime, eligible resident individuals can receive a Section 87A rebate of up to ₹60,000 where taxable income does not exceed ₹12 lakh.
Yes. Current published salary examples show monthly estimates above ₹70,000 under some salary structures.
Your employers may use different basic-salary percentages, PF arrangements, variable-pay structures, benefits and deductions.
Use your offer letter’s detailed breakup. Identify fixed pay, variable pay, employer contributions, gross salary and employee deductions. The net-pay figure on your payslip will ultimately provide the most accurate answer.
Final Takeaway
The most important number in a ₹9.5 LPA offer isn’t ₹79,167.
That number only comes from dividing the annual package by 12.
Your real monthly income depends on how much of the package is converted into regular salary and how much goes toward employer contributions, variable compensation and other components.
Current published examples place the 9.5 LPA in hand salary per month at roughly ₹67,500–₹75,500 under different assumptions.
So before accepting an offer, don’t ask only:
“What is the CTC?”
Ask:
“What is the fixed compensation, monthly gross and expected net salary after deductions?”
That three-part answer gives you a far more realistic picture of what your ₹9.5 LPA salary actually means for your monthly finances.
Read Our Tools: CTC Calculator | Download Salary Slip | Salary Tax Calculator

Hi, I’m Kashish Arora, an SEO specialist and finance content researcher passionate about simplifying salary and compensation topics. I create well-researched content on CTC, in-hand salary, salary structure, pay scales, salary slips, tax calculations, EPF, gratuity, bonuses, deductions, and employee benefits.
My articles are based on official government guidelines, employer policies, tax regulations, and other reliable public sources. I aim to explain complex payroll and taxation concepts in simple language so that employees, job seekers, HR professionals, and students can easily understand how salaries are calculated and how deductions affect take-home pay.
Along with payroll and taxation topics, I also cover salary insights for government employees, private-sector professionals, executives, and public personalities whenever reliable information is available.
Leave a Reply