
A ₹14.5 lakh salary package can be an exciting career milestone, but the number on your offer letter does not tell you exactly how much money you will receive every month. Before planning rent, savings, investments or loan payments, you need to understand how the company has divided your compensation.
The 14.5 LPA in hand salary depends on several factors, including your fixed salary, employer provident fund contribution, employee PF deduction, gratuity, variable pay and income tax.
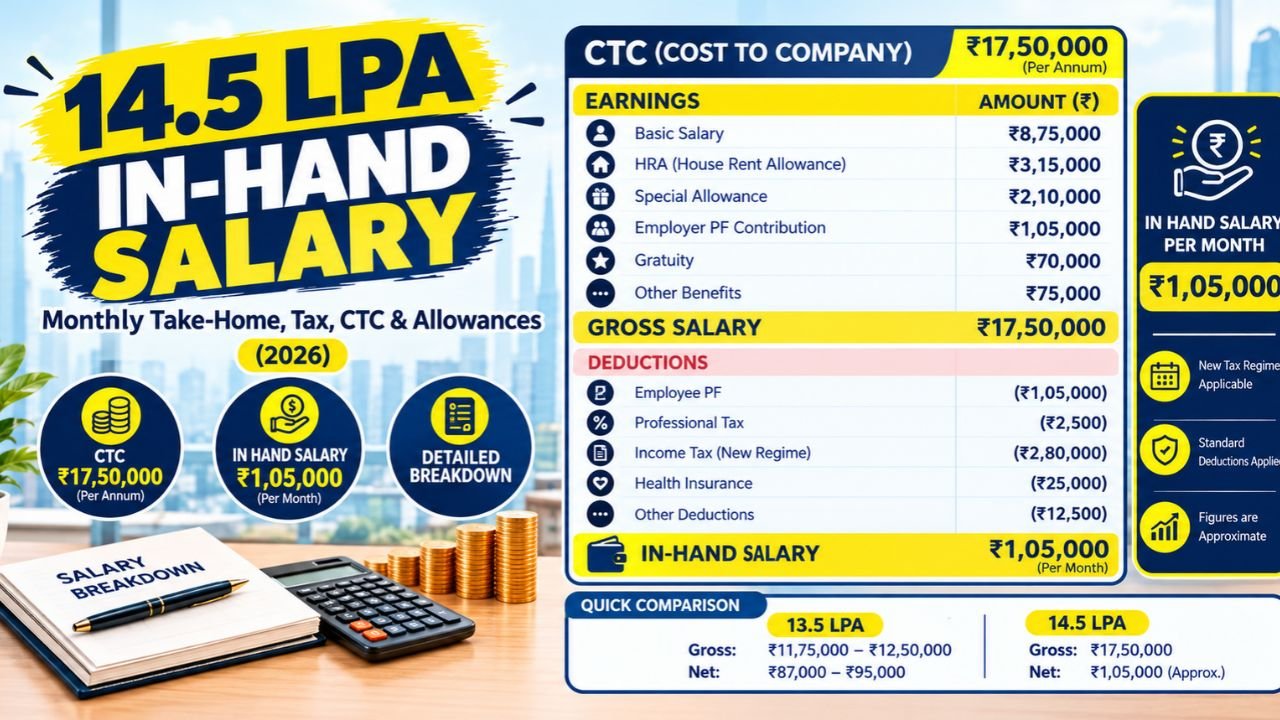
For a quick estimate, current salary calculators show approximately ₹97,337 to ₹1,03,044 per month under different salary structures and assumptions. These figures are not interchangeable: one model includes employer PF and gratuity within CTC, while another uses a different salary and deduction structure.
This guide explains what a ₹14.5 LPA package means in practical terms, how to estimate your monthly bank credit, what tax and PF can change, and how to evaluate an offer before accepting it. The calculations use the current 2026–27 tax-year context where applicable.
1. What Is 14.5 LPA in Hand Salary Per Month?
LPA means lakhs per annum. Therefore, a package of 14.5 LPA represents ₹14,50,000 in annual cost to company (CTC).
Dividing that amount by 12 gives:
₹14,50,000 ÷ 12 = ₹1,20,833.33 per month
This is the monthly equivalent of your annual CTC, not necessarily the salary credited to your bank account.
Your employer may include benefits and contributions in the CTC that you do not receive as monthly cash. Your employee PF contribution, income-tax withholding and other applicable deductions may then reduce the amount you receive.
CTC, gross salary and in-hand salary are different
- CTC: The total annual cost the employer associates with your employment.
- Gross salary: Your salary earnings before employee-side deductions, according to the employer’s payroll structure.
- In-hand salary: The amount remaining after applicable deductions and credited to your bank account.
[Reference Source: Employer compensation structure, EPFO and Income Tax Department]
This distinction matters because two companies can offer the same CTC but provide different monthly cash salaries.
2. How Does a ₹14.5 LPA Package Get Divided?
To estimate your take-home, start by identifying what is included in the advertised package.
A typical compensation structure may contain basic salary, house rent allowance (HRA), special allowance, employer PF, gratuity and performance-linked pay. The exact components and their proportions vary by employer.
Consider the following illustrative structure.
| Annual component | Example amount |
| Basic salary | ₹7,25,000 |
| HRA | ₹3,62,500 |
| Special allowance | ₹2,40,627 |
| Employer PF | ₹87,000 |
| Gratuity provision | ₹34,873 |
| Total CTC | ₹14,50,000 |
This is a worked example using a 50% basic-salary assumption, not a mandatory salary structure. A current calculator uses a similar breakdown for a ₹14.5 LPA package.
Why is the gross salary lower than CTC?
In this example, employer PF and the gratuity provision together account for approximately ₹1.22 lakh of the annual package.
After removing these components, the estimated gross salary is approximately ₹13.28 lakh annually, or around ₹1.11 lakh per month.
Your employee PF, income tax and any applicable professional tax are then considered when estimating the final bank credit.
Important: Gratuity is a benefit governed by applicable eligibility and payment rules. A gratuity amount shown within CTC should not be treated as monthly cash salary.
[Reference Source: Employer salary breakup and applicable gratuity rules]
3. PF Deduction on 14.5 LPA Salary
Provident Fund is one of the deductions worth checking carefully when comparing offers.
Under the standard EPF contribution framework, employee PF is commonly calculated at 12% of applicable PF wages. The exact contribution depends on the applicable rules and the employer’s arrangement. [Reference Source: Employees’ Provident Fund Organisation]
Example: PF calculated on basic salary
Suppose your basic salary is ₹7,25,000 annually.
Monthly basic salary:
₹7,25,000 ÷ 12 = ₹60,416.67
If employee PF is calculated at 12% of that amount:
₹60,416.67 × 12% = approximately ₹7,250 per month.
Annual employee PF would therefore be approximately ₹87,000 under this assumption. This is consistent with the PF figure used in the example salary structure above.
However, do not automatically calculate PF as 12% of the entire ₹14.5 lakh CTC. PF is linked to applicable PF wages, not simply the headline package.
Does a larger PF deduction mean a worse offer?
Not necessarily. Employee PF reduces the cash credited to your account, but it contributes to your provident-fund savings. Employer contributions may also form part of your overall compensation.
When comparing two jobs, examine both your monthly cash requirement and the long-term benefits included in each package.
[Reference Source: EPFO contribution-rate documentation]
Read More : 13 LPA In Hand Salary in India 2026: Monthly Take-Home, CTC, PF, Tax & Salary Breakup
4. Income Tax on 14.5 LPA in FY 2026–27
Income tax can make a noticeable difference to the amount you receive each month. However, the tax calculation should be based on your taxable income, not merely the CTC displayed on your offer letter.
The Ministry of Finance’s published tax rates for Tax Year 2026–27 under the new regime are as follows.
| Taxable income | New-regime rate |
| Up to ₹4 lakh | Nil |
| ₹4 lakh–₹8 lakh | 5% |
| ₹8 lakh–₹12 lakh | 10% |
| ₹12 lakh–₹16 lakh | 15% |
| ₹16 lakh–₹20 lakh | 20% |
| ₹20 lakh–₹24 lakh | 25% |
| Above ₹24 lakh | 30% |
The applicable rules also provide a ₹75,000 standard deduction for eligible salaried taxpayers under the new regime. The actual calculation depends on the tax law applicable to the relevant year and your personal circumstances. [Reference Source: Ministry of Finance, Union Budget and tax legislation]
An illustrative tax calculation
One current salary-calculator model estimates the following for a ₹14.5 LPA CTC:
| Item | Estimated annual amount |
| CTC | ₹14,50,000 |
| Gross salary after removing employer PF and gratuity | ₹13,28,128 |
| Standard deduction | ₹75,000 |
| Illustrative taxable salary | ₹12,53,128 |
| Estimated tax, including cess | ₹70,688 |
These are the assumptions and results used by that particular calculator, not a guaranteed assessment of your personal tax liability.
Actual tax can differ if your salary structure changes, you have other taxable income, or your circumstances differ from those assumed in the model.
Is zero income tax possible at 14.5 LPA?
You should not assume that every employee earning ₹14.5 LPA will have zero tax. In the worked example above, the estimated taxable salary exceeds ₹12 lakh and the calculator produces a tax liability.
Use an official tax resource or a qualified tax professional to confirm your own liability. Online salary calculators are useful for estimates, but they cannot establish your exact tax position without the relevant details.
[Reference Source: Ministry of Finance, Tax Year 2026–27 tax rates]
5. Why Different Calculators Show Different In-Hand Salaries
Suppose you search for “14.5 LPA in hand salary per month.” One website shows ₹97,337, while another shows ₹1,03,044.
The difference does not automatically mean one result is wrong. The calculators may be using different assumptions about the salary breakup, PF wages, tax calculations and employer contributions.
Here are the main factors to compare.
Basic salary percentage
If basic salary is higher, PF calculated as a percentage of basic may also be higher. This can reduce monthly cash take-home while increasing the employee’s PF contribution.
Employer PF and gratuity
Some employers include these amounts inside the headline CTC. A calculator that treats them differently can produce a different gross salary and take-home estimate.
Professional tax
Professional tax rules and amounts vary by state. A calculator using a default state setting may not match the deductions on your own payslip.
Variable compensation
If the CTC includes a performance bonus, retention payment or other variable component, the full annual package may not be paid as regular monthly salary.
Best practice: Use a calculator as a starting point, then replace its assumptions with the figures from your actual offer letter.
6. Three Practical Examples of a ₹14.5 LPA Offer
To see why the package alone is not enough, consider three hypothetical candidates.
Candidate A: Mostly fixed compensation
The company offers a package dominated by fixed salary, with a clearly documented monthly gross and relatively little variable pay.
This candidate can budget around a more predictable monthly income, although PF and tax deductions still apply.
Candidate B: A larger performance bonus
The offer includes a substantial annual bonus inside the ₹14.5 lakh CTC. The candidate may not receive that bonus every month, and the eventual payout could depend on performance conditions.
Even if the advertised CTC is identical, the regular monthly bank credit may be lower.
Candidate C: Different PF treatment
The third candidate receives the same headline CTC but has a different PF wage basis or employer compensation structure.
That can change the amount deducted from monthly salary and therefore the take-home amount.
These examples illustrate how compensation structures affect cash flow; they are not claims about any specific employer.
7. Can You Live Comfortably on a ₹14.5 LPA Salary?
Whether this salary feels comfortable depends on your city, housing costs, family commitments, debts and savings goals.
If your actual take-home is around ₹1 lakh a month, planning around that bank-credit figure is more useful than budgeting around ₹1,20,833.
For example, you could divide your monthly income into:
- Housing and utilities
- Food and transportation
- Insurance and essential payments
- Emergency savings
- Investments and long-term goals
- Personal spending
There is no single allocation that suits everyone. Someone living with family may have very different expenses from someone renting an apartment in a high-cost city.
The key is to build a budget around your confirmed net salary, not the annual CTC divided by 12.
Read More: 13.5 LPA In Hand Salary: How Much Will You Actually Get Every Month in 2026?
8. Common Mistakes When Calculating 14.5 LPA In-Hand Salary
Mistake 1: Treating monthly CTC as monthly salary
₹1,20,833 is the monthly CTC equivalent, not a guaranteed bank credit.
Solution: Ask HR for monthly gross salary and estimated net pay.
Mistake 2: Ignoring the variable component
A package containing a bonus is not the same as an entirely fixed package.
Solution: Separate guaranteed compensation from performance-linked payments.
Mistake 3: Assuming every employee has the same PF deduction
PF treatment depends on applicable wages and the employer’s arrangement.
Solution: Confirm your monthly employee contribution with payroll.
Mistake 4: Copying a tax figure from another website
Salary calculators may use different tax and salary assumptions.
Solution: Calculate your own tax using the applicable official rules and your actual income details.
Mistake 5: Comparing jobs only by CTC
A headline package does not show the complete cash-flow picture.
Solution: Compare fixed pay, monthly gross, take-home, variable pay, benefits and career opportunities together.
9. What to Check Before Accepting a ₹14.5 LPA Offer
Before signing, ask the recruiter or HR team for a complete salary breakup. Confirm the following:
- Annual CTC and annual fixed compensation
- Monthly gross salary
- Employee PF deduction
- Employer PF contribution
- Gratuity and insurance components
- Performance bonus or variable pay
- Expected TDS under the applicable tax regime
- Any other monthly deductions
- The approximate amount credited to your bank account
If the employer provides these details, you can estimate your monthly take-home far more accurately than by relying on the CTC alone.
10. What May Change in Salary Calculations Going Forward?
Salary estimates can change when tax rules, payroll policies, PF treatment or employer compensation structures change. Online calculators should therefore identify the financial year and state their assumptions clearly.
For employees, the useful habit is to check the relevant official tax rules each year and compare those rules with the latest salary breakup. That is more reliable than reusing an old take-home figure from a different year.
[Reference Source: Ministry of Finance and EPFO]
Frequently Asked Questions
Current online calculators provide examples of approximately ₹97,337 to ₹1,03,044 per month under different assumptions. Your actual take-home depends on the salary breakup, PF, tax, professional tax and variable pay.
₹14.5 lakh divided by 12 equals approximately ₹1,20,833 per month. This is the monthly CTC equivalent, not necessarily the amount deposited in your bank account.
It depends on applicable PF wages and the employer’s arrangement. In an example with basic salary of ₹60,416.67 per month, a 12% employee contribution would be approximately ₹7,250 per month.
There is no universal tax figure for every ₹14.5 LPA employee. One current calculator estimates annual tax of ₹70,688 under its stated FY 2026–27 assumptions. Your actual tax can differ.
It can be a strong package, but its practical value depends on your location, household expenses, responsibilities, job benefits and financial goals.
It may. Employer PF is often included in CTC, so check the compensation table rather than assuming the entire annual amount is paid as cash.
Start with the monthly gross salary, then account for employee PF, TDS, professional tax and any other applicable deductions. If your CTC includes variable or non-cash components, identify those separately before calculating your regular monthly income.
Conclusion: Understand Your Salary Before You Accept the Offer
A 14.5 LPA package equals ₹14,50,000 per year, or approximately ₹1,20,833 per month as a CTC equivalent. Your actual take-home will be lower or otherwise different depending on how the employer structures the package and what deductions apply.
Current calculator examples place monthly take-home around ₹97,337 to ₹1,03,044 under different assumptions. Treat those numbers as reference points, not promises.
Before accepting an offer, confirm the fixed salary, monthly gross, PF contribution, tax estimate and variable-pay conditions. Those details will tell you what you can realistically expect to receive and help you make a better-informed career decision.
Read Our Tools: CTC Calculator | Download Salary Slip | Salary Tax Calculator

Hi, I’m Kashish Arora, an SEO specialist and finance content researcher passionate about simplifying salary and compensation topics. I create well-researched content on CTC, in-hand salary, salary structure, pay scales, salary slips, tax calculations, EPF, gratuity, bonuses, deductions, and employee benefits.
My articles are based on official government guidelines, employer policies, tax regulations, and other reliable public sources. I aim to explain complex payroll and taxation concepts in simple language so that employees, job seekers, HR professionals, and students can easily understand how salaries are calculated and how deductions affect take-home pay.
Along with payroll and taxation topics, I also cover salary insights for government employees, private-sector professionals, executives, and public personalities whenever reliable information is available.
One response to “14.5 LPA In Hand Salary in India 2026: Monthly Salary, Tax and PF Breakdown”
[…] Check Also: 14.5 LPA In Hand Salary in India 2026: Monthly Salary, Tax and PF Breakdown […]