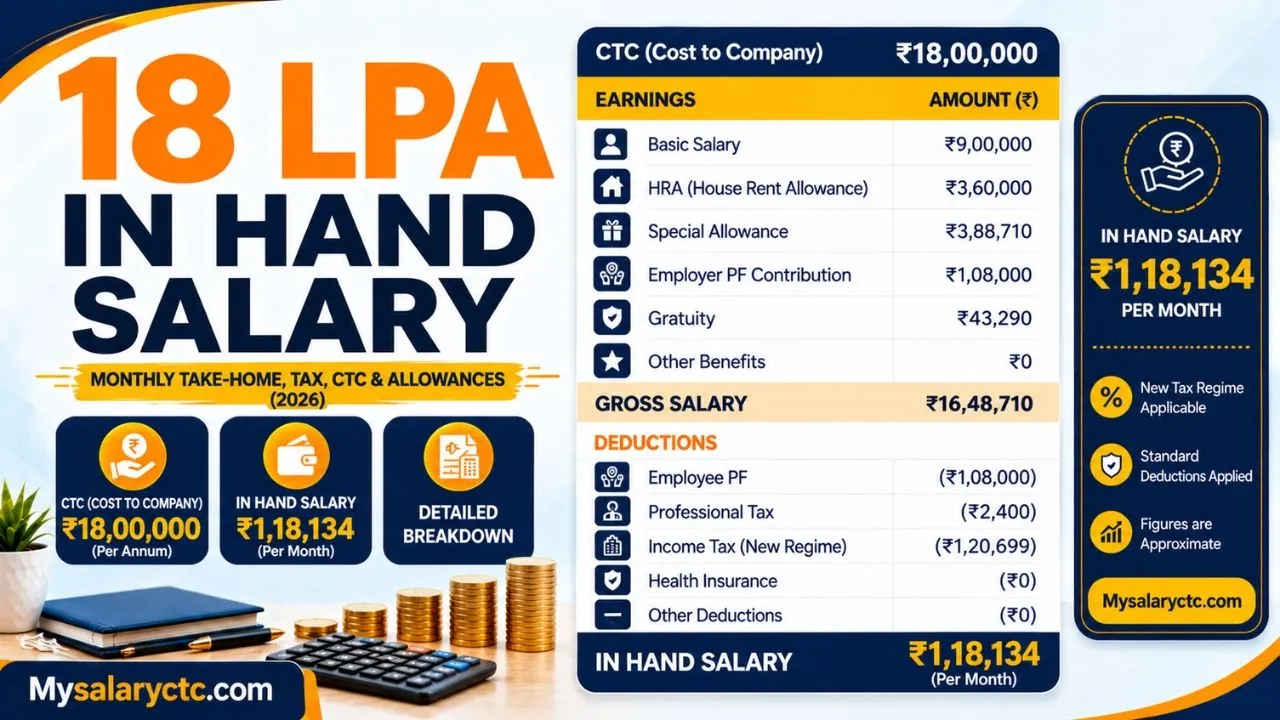

An annual package of ₹18 LPA may look like a salary of ₹1.5 lakh per month, but the actual amount credited to your bank account is usually lower. This is because your Cost to Company (CTC) includes several components, such as employer Provident Fund (PF), gratuity, insurance and, in some cases, variable pay. Income tax, employee PF and professional tax further reduce your monthly take-home salary. The 18 LPA In Hand Salary depends on the company’s salary structure, applicable tax regime and deductions. Under an illustrative salary structure with 50% basic pay, employer and employee PF contributions of 12% of basic salary, gratuity and the new tax regime, the estimated monthly take-home salary is approximately ₹1,18,134.
However, this is not a fixed amount for everyone earning ₹18 LPA. Employees with capped PF contributions, different basic salary percentages or variable compensation may receive a different amount. This guide explains the complete ₹18 lakh salary breakup, income tax calculation, PF deductions and differences between the old and new tax regimes to help you estimate your actual monthly salary.
18 LPA In Hand Salary Per Month
An employee earning ₹18 LPA has an annual CTC of ₹18,00,000, equivalent to ₹1,50,000 per month. However, the monthly CTC equivalent should not be confused with gross salary or in-hand salary. Under the sample salary structure used in this article, the estimated monthly take-home salary is approximately ₹1.18 lakh after employee PF, professional tax and income tax deductions.
Here is a quick overview:
| Salary Component | Amount |
| Annual CTC | ₹18,00,000 |
| Monthly CTC | ₹1,50,000 |
| Annual gross salary | ₹16,48,710 |
| Employer PF | ₹1,08,000 |
| Gratuity provision | ₹43,290 |
| Employee PF | ₹1,08,000 |
| Annual professional tax | ₹2,400 |
| Estimated annual income tax | ₹1,20,699 |
| Estimated annual in-hand salary | ₹14,17,611 |
| Estimated monthly in-hand salary | ₹1,18,134 |
Note: This is an illustrative calculation based on a specific salary structure and the new tax regime for Tax Year 2026-27. Actual take-home pay depends on the employer’s compensation policy and applicable statutory deductions.
The monthly in-hand amount can be higher if PF contributions are restricted to the applicable statutory ceiling rather than calculated on the entire basic salary. Similarly, employees receiving performance-linked bonuses may have a lower regular monthly salary even when their annual CTC is ₹18 lakh.
18 LPA Salary Breakdown: CTC vs Gross vs In-Hand Salary
Before calculating the take-home salary, it is important to understand the difference between CTC, gross salary and in-hand salary.
Cost to Company (CTC): CTC is the total annual cost an employer incurs for employing someone. It can include basic salary, HRA, special allowance, employer PF, gratuity, insurance and variable compensation.
Gross Salary: Gross salary is the salary payable before employee-side deductions such as PF, professional tax and TDS. It generally excludes employer contributions and other non-cash CTC components.
In-Hand Salary: In-hand salary is the amount an employee receives in their bank account after applicable deductions. It is also known as take-home salary or net salary.
For an 18 LPA package, the difference between these three amounts can be significant. For example, although the monthly CTC is ₹1.5 lakh, the gross monthly salary in our sample calculation is approximately ₹1.37 lakh, while the estimated in-hand amount is ₹1.18 lakh.
Complete 18 LPA CTC Salary Structure
For a practical example, consider an employee whose annual CTC is ₹18 lakh and whose basic salary represents 50% of the total CTC.
The employer contributes 12% of basic salary towards PF and includes gratuity in the CTC. There is no variable pay or additional annual bonus in this example.
| Salary Component | Annual Amount |
| Basic Salary | ₹9,00,000 |
| House Rent Allowance (HRA) | ₹3,60,000 |
| Special Allowance | ₹3,88,710 |
| Employer PF Contribution | ₹1,08,000 |
| Gratuity | ₹43,290 |
| Total CTC | ₹18,00,000 |
In this example, the annual gross cash salary is ₹16,48,710, which includes basic salary, HRA and special allowance. Employer PF and gratuity are included in the CTC but are not paid as regular monthly cash salary.
This is why an employee cannot simply divide ₹18 lakh by 12 and expect ₹1.5 lakh to be credited every month.
18 LPA In Hand Salary Under the New Tax Regime
The new tax regime is the default tax regime for eligible individual taxpayers in India. It offers lower income tax slab rates but restricts several deductions and exemptions available under the old regime.
For Tax Year 2026-27, the new regime follows the revised tax slabs, with income up to ₹4 lakh being tax-free and rates increasing progressively for higher income brackets.
For an employee earning ₹18 LPA, the actual tax liability depends on taxable salary rather than the total CTC.
New Tax Regime Tax Slabs for 2026-27
| Taxable Annual Income | Income Tax Rate |
| Up to ₹4,00,000 | Nil |
| ₹4,00,001–₹8,00,000 | 5% |
| ₹8,00,001–₹12,00,000 | 10% |
| ₹12,00,001–₹16,00,000 | 15% |
| ₹16,00,001–₹20,00,000 | 20% |
| ₹20,00,001–₹24,00,000 | 25% |
| Above ₹24,00,000 | 30% |
Salaried taxpayers opting for the new regime can claim a standard deduction of ₹75,000. However, the actual taxable income also depends on other eligible income and adjustments.
Income Tax Calculation on an 18 LPA Salary
Using the sample salary structure mentioned earlier, the annual gross salary is ₹16,48,710.
The calculation is:
| Particulars | Amount |
| Annual gross salary | ₹16,48,710 |
| Standard deduction | -₹75,000 |
| Taxable income | ₹15,73,710 |
The income tax is calculated across the applicable slabs rather than by applying one tax rate to the entire taxable income.
| Tax Slab | Calculation | Tax Amount |
| Up to ₹4 lakh | No tax | ₹0 |
| ₹4 lakh–₹8 lakh | 5% of ₹4 lakh | ₹20,000 |
| ₹8 lakh–₹12 lakh | 10% of ₹4 lakh | ₹40,000 |
| ₹12 lakh–₹15,73,710 | 15% of ₹3,73,710 | ₹56,057 |
| Total income tax before cess | ₹1,16,057 | |
| Health and Education Cess | 4% | ₹4,642 |
| Total annual income tax | ₹1,20,699 |
Therefore, the estimated annual income tax on this salary structure is approximately ₹1.21 lakh.
The monthly TDS deduction, assuming it is spread equally across 12 months, comes to approximately ₹10,058. Employers may adjust monthly TDS depending on declarations, previous salary, bonuses and other taxable income.
18 LPA In Hand Salary Under the Old Tax Regime
The old tax regime offers higher tax slab rates but allows salaried employees to claim several deductions and exemptions. These include eligible investments under Section 80C, health insurance premiums under Section 80D, HRA exemption and certain other deductions, subject to the applicable conditions.
For someone earning ₹18 LPA, choosing between the old and new tax regimes depends on their eligible deductions, exemptions and salary components.
Under the sample salary structure, the gross annual salary is ₹16,48,710. Assuming a standard deduction of ₹50,000 and no additional deductions or exemptions, the taxable income would be ₹15,98,710.
The illustrative tax calculation is:
| Tax Slab | Tax Calculation | Tax Amount |
| Up to ₹2.5 lakh | Nil | ₹0 |
| ₹2.5 lakh–₹5 lakh | 5% of ₹2.5 lakh | ₹12,500 |
| ₹5 lakh–₹10 lakh | 20% of ₹5 lakh | ₹1,00,000 |
| ₹10 lakh–₹15,98,710 | 30% of ₹5,98,710 | ₹1,79,613 |
| Total income tax | ₹2,92,113 | |
| Health and Education Cess (4%) | ₹11,685 | |
| Total annual tax | ₹3,03,798 |
Under these assumptions, the old regime results in an annual tax liability of approximately ₹3.04 lakh, compared with approximately ₹1.21 lakh under the new regime.
However, this is a comparison without additional old-regime deductions or exemptions. An employee paying rent, investing in eligible tax-saving instruments or claiming other eligible deductions may have a lower tax liability under the old regime.
Therefore, employees should calculate their tax under both regimes before deciding which one is more beneficial.
18 LPA Salary: New Tax Regime vs Old Tax Regime
The choice of tax regime can significantly affect the monthly take-home salary of someone earning ₹18 LPA.
The following comparison uses the same gross salary and PF assumptions for both regimes.
| Particulars | New Tax Regime | Old Tax Regime |
| Annual CTC | ₹18,00,000 | ₹18,00,000 |
| Annual gross salary | ₹16,48,710 | ₹16,48,710 |
| Standard deduction | ₹75,000 | ₹50,000 |
| Other deductions/exemptions | Not included | Not included |
| Taxable income | ₹15,73,710 | ₹15,98,710 |
| Annual income tax including cess | ₹1,20,699 | ₹3,03,798 |
| Employee PF | ₹1,08,000 | ₹1,08,000 |
| Professional tax | ₹2,400 | ₹2,400 |
| Estimated annual take-home | ₹14,17,611 | ₹12,34,512 |
| Estimated monthly take-home | ₹1,18,134 | ₹1,02,876 |
These are illustrative estimates. The old-regime calculation assumes no HRA exemption or additional deductions, while the new-regime calculation uses the applicable standard deduction. Actual results can change based on eligible tax benefits and payroll treatment.
In this particular example, the new tax regime provides a higher monthly take-home salary. However, an employee with substantial eligible deductions under the old regime should compare both calculations before making a decision.
Monthly Salary Slip for 18 LPA
A salary slip helps employees understand how their annual package is converted into monthly earnings and deductions. Based on the sample 18 LPA salary structure, the monthly salary components are as follows:
Monthly Earnings
| Earnings Component | Monthly Amount |
| Basic Salary | ₹75,000 |
| House Rent Allowance | ₹30,000 |
| Special Allowance | ₹32,393 |
| Total Monthly Gross Salary | ₹1,37,393 |
Monthly Deductions
| Deduction Component | Monthly Amount |
| Employee PF | ₹9,000 |
| Professional Tax | ₹200 |
| Income Tax (TDS) | ₹10,058 |
| Total Monthly Deductions | ₹19,258 |
Estimated Monthly Take-Home Salary
| Particulars | Amount |
| Monthly Gross Salary | ₹1,37,393 |
| Total Deductions | ₹19,258 |
| Net Monthly Salary | ₹1,18,135 |
The small difference between this rounded payslip and the earlier annual calculation is due to rounding of monthly salary components.
This example assumes that the annual tax liability is divided equally across 12 months. Actual payslips may show different TDS amounts because employers adjust tax deductions throughout the year.
Also, employer PF and gratuity are not included in monthly earnings because they are already accounted for as employer-side CTC components.
How PF Affects Your 18 LPA In-Hand Salary
Employee Provident Fund (EPF) is one of the important deductions that affects monthly take-home salary. Both the employer and employee contribute towards the employee’s provident fund, subject to applicable statutory provisions and the employer’s contribution policy.
In many salary structures, the employee contributes 12% of basic salary towards PF. The employer also makes a contribution, which is generally included in the CTC.
For an employee earning ₹18 LPA with a basic salary of ₹75,000 per month, the employee PF contribution would be ₹9,000 per month if contributions are calculated on the full basic salary.
However, not all employers calculate PF on the entire basic salary. Some contribution arrangements are restricted to the applicable statutory wage ceiling.
EPF Wage Ceiling Update in September 2026
An important development affecting PF calculations occurred in September 2026. The government increased the statutory wage ceiling for mandatory EPF coverage from ₹15,000 to ₹25,000 per month, effective September 17, 2026.
According to the Ministry of Labour and Employment, the revision is intended to extend mandatory social security coverage to additional eligible employees earning between ₹15,000 and ₹25,000 per month.
For employees whose contributions are restricted to the revised ceiling, the maximum employee contribution at 12% would be ₹3,000 per month, compared with ₹1,800 under the previous ₹15,000 ceiling. The actual contribution depends on applicable membership and scheme provisions. Source: Press Information Bureau.
PF Contribution Comparison for an 18 LPA Salary
| PF Calculation Method | Monthly PF Wage | Employee Contribution (12%) |
| Full basic salary | ₹75,000 | ₹9,000 |
| Revised statutory ceiling | ₹25,000 | ₹3,000 |
The difference between these two contribution methods is ₹6,000 per month.
If an employer calculates PF on the full basic salary, the employee’s monthly take-home salary will be lower. If contributions are restricted to the applicable ceiling, the immediate take-home amount can be higher, although the retirement savings contribution will also be lower.
Importantly, the revised ₹25,000 ceiling does not mean that every employee earning ₹18 LPA will automatically have PF deducted on ₹25,000. Existing membership, applicable statutory rules and employer contribution arrangements must be considered.
Factors That Affect Your 18 LPA Monthly Take-Home Salary
Two employees earning the same annual CTC can receive different monthly salaries. This happens because companies follow different compensation structures and employees may have different tax deductions.
Here are some important factors that affect the 18 LPA in-hand salary.
1. Basic Salary Percentage
Basic salary is an important component of the salary structure because several other components, including PF and gratuity, are calculated with reference to it.
For example, if basic salary represents 50% of an ₹18 lakh CTC, the annual basic salary is ₹9 lakh. If the employer uses a different basic salary percentage, the PF and gratuity amounts may change.
2. Employer and Employee PF Contributions
Employee PF is deducted from monthly salary, while employer PF is generally included in the CTC.
A company calculating PF on full basic salary will generally show a higher employee-side deduction than one restricting contributions to the applicable statutory ceiling.
3. Gratuity
Gratuity is an employer-funded retirement benefit payable subject to applicable eligibility conditions. It is often included in the CTC as an annual provision.
In the sample calculation, gratuity is estimated at approximately 4.81% of basic salary, or ₹43,290 annually.
Although it forms part of the CTC, this amount is not normally credited to the employee every month.
4. Variable Pay and Performance Bonuses
Some employers include performance-linked incentives or annual bonuses in the ₹18 LPA package.
For example, consider two employees:
| Particulars | Employee A | Employee B |
| Total CTC | ₹18 lakh | ₹18 lakh |
| Fixed CTC | ₹18 lakh | ₹16 lakh |
| Variable Pay | ₹0 | ₹2 lakh |
Employee A has an entirely fixed package, while Employee B receives ₹2 lakh as performance-linked compensation.
Employee B may receive a lower regular monthly salary because the variable component is paid separately, depending on performance and company policy.
5. Professional Tax
Professional tax is a state-level tax imposed on salaried employees and certain professionals. Its amount and applicability vary depending on the state.
For this article’s sample calculation, professional tax is assumed to be ₹2,400 annually. However, the actual deduction can be different depending on the employee’s work location and applicable state rules.
6. Health Insurance and Other Benefits
Some companies include group health insurance, life insurance, meal benefits, transport allowances and other employee benefits in the CTC.
These benefits may increase the total package value without directly increasing the monthly bank credit.
7. Income Tax Regime
The selected tax regime directly affects the amount deducted as TDS.
The new regime generally offers lower slab rates, while the old regime provides access to more deductions and exemptions. Employees should evaluate their individual tax position instead of selecting a regime based only on the headline tax rates.
Is 18 LPA a Good Salary in India?
An annual salary of ₹18 LPA is a competitive compensation package for many professionals in India, particularly those working in IT, software development, consulting, finance and other specialised industries.
However, whether it is a good salary depends on the employee’s location, experience, financial responsibilities and lifestyle.
With an estimated monthly take-home salary of approximately ₹1.18 lakh under our sample calculation, an employee can manage several regular expenses while also saving and investing a portion of their income.
For example, someone living in a city with moderate rental costs may be able to allocate their monthly income towards the following:
| Expense Category | Illustrative Monthly Budget |
| House Rent | ₹20,000 |
| Groceries and Food | ₹12,000 |
| Transportation | ₹6,000 |
| Utilities and Internet | ₹4,000 |
| Entertainment and Shopping | ₹8,000 |
| Insurance and Medical Expenses | ₹5,000 |
| Family and Personal Expenses | ₹10,000 |
| Savings and Investments | ₹35,000 |
| Emergency Fund and Other Expenses | ₹18,134 |
| Total | ₹1,18,134 |
This is only an example of how someone might distribute their monthly take-home salary. Actual expenses will vary considerably between cities, particularly in locations such as Mumbai, Bengaluru, Delhi and Hyderabad.
Overall, an 18 LPA package can provide a comfortable financial foundation, provided the employee manages expenses, maintains emergency savings and plans investments according to their financial goals.
Conclusion
The 18 LPA In Hand Salary is not the same as the monthly CTC of ₹1.5 lakh. Under the sample salary structure explained in this article, an employee can expect approximately ₹1,18,134 per month after employee PF, professional tax and income tax deductions under the new tax regime.
However, the actual take-home salary can vary depending on basic salary, employer PF contributions, gratuity, variable pay and the selected tax regime. The September 2026 increase in the EPF wage ceiling is another important factor that employees should consider while reviewing their salary calculations.
Before accepting an ₹18 LPA job offer, carefully examine the compensation breakup rather than focusing only on the headline CTC. Understanding fixed pay, variable compensation, PF, gratuity and income tax will help you estimate your actual monthly earnings and make a more informed financial decision.
Frequently Asked Questions
1. What is the 18 LPA in-hand salary per month?
The estimated 18 LPA in-hand salary is approximately ₹1,18,134 per month under a sample salary structure with 50% basic pay, full-basic PF contributions, gratuity and the new tax regime. The actual amount depends on the employer’s salary breakup and applicable deductions.
2. What is the monthly salary for an 18 LPA package?
An annual package of ₹18 lakh is equivalent to ₹1,50,000 per month in CTC terms. However, the actual gross salary and in-hand amount are lower after excluding employer-side contributions and deducting applicable taxes and other deductions.
3. How much income tax is applicable on an 18 LPA salary?
Under the illustrative salary structure used in this article, the annual income tax under the new regime is approximately ₹1,20,699, including 4% health and education cess. The calculation assumes an annual gross salary of ₹16,48,710 and a standard deduction of ₹75,000.
4. Is 18 LPA a good salary in India?
Yes, ₹18 LPA can be a good salary in India for many professionals. However, the actual financial comfort depends on the city, monthly expenses, family responsibilities, housing costs and savings goals.
5. How much PF is deducted from an 18 LPA salary?
PF deductions depend on the basic salary and the employer’s contribution policy. If the basic salary is ₹75,000 per month and PF is calculated at 12% of the entire basic salary, the employee contribution is ₹9,000 monthly. If contributions are restricted to the applicable ₹25,000 statutory ceiling, the corresponding 12% contribution would be ₹3,000, subject to the applicable rules.
6. What is the difference between 18 LPA fixed salary and 18 LPA CTC?
An 18 LPA fixed salary generally refers to fixed annual compensation, whereas CTC can include employer PF, gratuity, insurance and variable pay. Therefore, an 18 LPA CTC package may have a lower fixed cash component than an 18 LPA fixed-pay package.
7. Which tax regime is better for an 18 LPA salary?
The new tax regime may be more beneficial for employees who do not have substantial eligible deductions and exemptions. The old regime can be worth considering for employees claiming HRA exemption, eligible investments and other deductions. Comparing the actual tax liability under both regimes is the best way to decide.
8. Does an 18 LPA salary mean ₹1.5 lakh per month in hand?
No. ₹1.5 lakh is the monthly CTC equivalent, not the take-home salary. Employer PF, gratuity, insurance, variable pay, employee PF, income tax and other deductions can reduce the amount credited to the bank account.
9. What is the 18 LPA salary after tax under the new regime?
For the sample salary structure in this article, the annual income tax under the new regime is approximately ₹1.21 lakh. After accounting for employee PF and professional tax, the estimated annual take-home salary is ₹14.18 lakh, or approximately ₹1.18 lakh per month.
10. Does variable pay affect the 18 LPA in-hand salary?
Yes. If a company includes performance-linked incentives in the ₹18 LPA CTC, the regular monthly salary may be lower because the variable component is paid separately. The actual bonus also depends on the company’s performance and payout policy.

Hi, I’m Kashish Arora, an SEO specialist and finance content researcher passionate about simplifying salary and compensation topics. I create well-researched content on CTC, in-hand salary, salary structure, pay scales, salary slips, tax calculations, EPF, gratuity, bonuses, deductions, and employee benefits.
My articles are based on official government guidelines, employer policies, tax regulations, and other reliable public sources. I aim to explain complex payroll and taxation concepts in simple language so that employees, job seekers, HR professionals, and students can easily understand how salaries are calculated and how deductions affect take-home pay.
Along with payroll and taxation topics, I also cover salary insights for government employees, private-sector professionals, executives, and public personalities whenever reliable information is available.