
Last Updated: October 20, 2026
A ₹40 lakh annual salary package is an attractive offer for experienced professionals in India. However, a ₹40 LPA package does not mean you will receive ₹3.33 lakh directly in your bank account every month. Your actual take-home pay depends on your salary structure, income tax, employee provident fund (EPF), professional tax, and variable components.
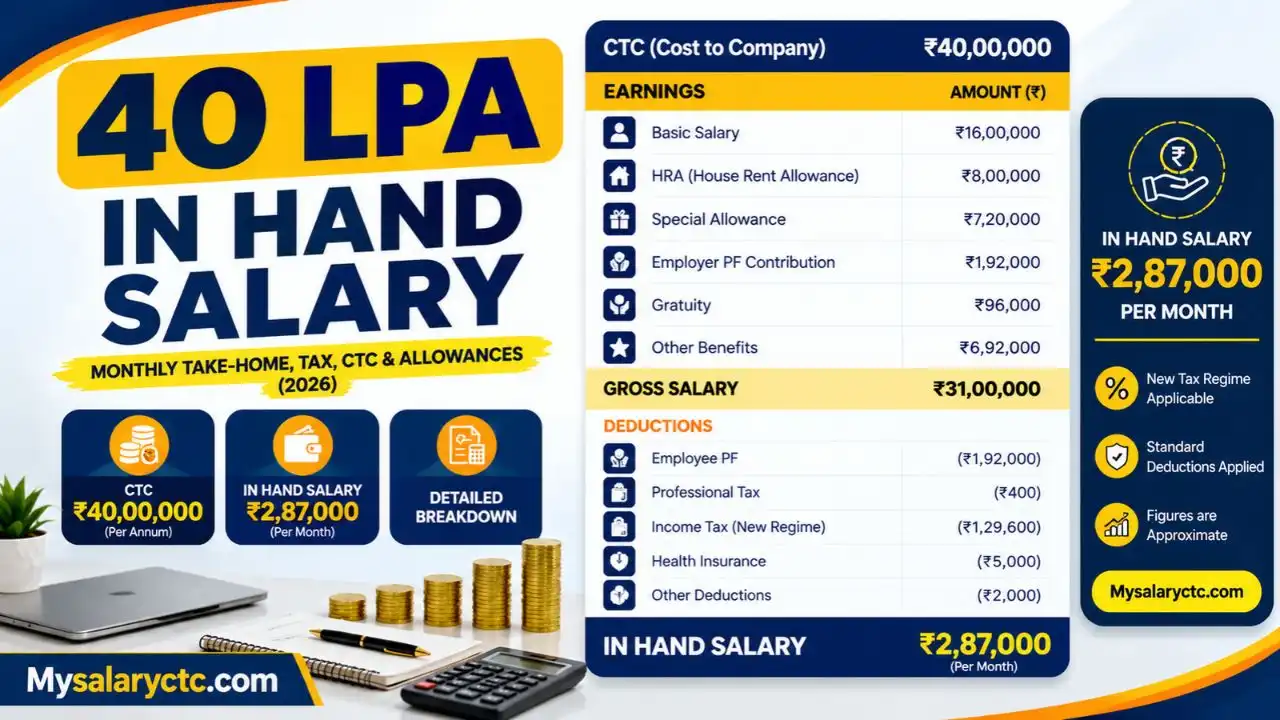
For anyone searching for a 40 LPA in hand salary in India, a reasonable starting estimate is approximately ₹2.25 lakh to ₹2.45 lakh per month under common salary structures and the new tax regime. The exact amount can differ significantly depending on how the employer structures the CTC.
This guide explains the monthly in-hand salary, estimated tax deductions, salary breakup, old versus new tax regimes, and the factors to check before accepting a ₹40 lakh offer.
40 LPA In Hand Salary Overview
Here is a quick overview of the estimated take-home salary for a ₹40 lakh CTC package in India.
| Salary component | Estimated amount |
| Annual CTC | ₹40,00,000 |
| Monthly CTC | ₹3,33,333 |
| Estimated monthly in-hand salary | ₹2.28–₹2.45 lakh |
| Estimated annual take-home | ₹27.4–₹29.4 lakh |
| Applicable income tax | Yes |
| Main deductions | Income tax, employee PF and professional tax |
These estimates reflect different salary structures and calculation assumptions published by salary calculators. For example, SalaryInHand estimates ₹2,28,208 monthly, while Flexiple estimates ₹2,40,467 under its default assumptions for FY 2026–27. Neither figure is guaranteed for every employee.
Check Also: 25 LPA In Hand Salary: Monthly Take-Home, Tax & Salary Breakup (2026–27)
What Is the 40 LPA In Hand Salary Per Month?
The 40 LPA in hand salary per month depends on whether the ₹40 lakh package includes employer PF, gratuity, annual bonuses, and other benefits. Dividing ₹40,00,000 by 12 gives a monthly CTC of ₹3,33,333. However, this is the employer’s total annual cost, not necessarily the amount you receive as gross monthly salary. After accounting for employer contributions, income tax, and employee deductions, your monthly bank credit may be around ₹2.3 lakh to ₹2.4 lakh under a typical fixed-pay structure.
Consider these illustrative scenarios:
| Scenario | Estimated monthly take-home |
| Higher deductions and PF contributions | ₹2.28 lakh |
| Standard salary structure | ₹2.35 lakh |
| Lower PF deductions and higher cash component | ₹2.45 lakh |
The final amount can fall outside this range if a large part of your package consists of performance bonuses, stock compensation or other non-monthly benefits.
40 LPA Salary Breakdown: CTC vs Gross Salary vs In-Hand
Understanding the difference between CTC, gross salary and net salary is essential when evaluating a high-paying job offer.
- CTC: The total annual cost incurred by the employer, including employer contributions and eligible benefits.
- Gross salary: Your salary before employee-side deductions such as income tax and PF.
- In-hand salary: The amount credited to your bank account after applicable deductions.
For example, an employer may offer ₹40 lakh CTC but include employer PF, gratuity and insurance benefits in that figure. These components increase the package value without necessarily increasing your monthly bank credit.
The following is an illustrative salary structure, not a universal breakup.
| Salary component | Annual amount |
| Basic salary | ₹16,00,000 |
| House Rent Allowance (HRA) | ₹8,00,000 |
| Special allowance | ₹10,50,000 |
| Employer PF contribution | ₹1,92,000 |
| Gratuity provision | ₹77,000 |
| Bonus and other benefits | ₹2,81,000 |
| Total CTC | ₹40,00,000 |
In this example, the employer’s PF contribution and gratuity provision are included in the CTC. The bonus and other benefits may also have different payment schedules. Consequently, the monthly gross salary available for payroll calculations is lower than ₹3.33 lakh.
Check Also: 14 LPA In Hand Salary: Monthly Take-Home, Tax & Salary Breakup
40 LPA In Hand Salary After Tax
Income tax is one of the largest deductions from a ₹40 lakh salary. Your tax liability depends on your taxable income, the selected tax regime and eligible deductions. Under the new tax regime applicable for FY 2026–27, the standard deduction for salaried employees is ₹75,000. The tax slabs rise progressively, with income above ₹24 lakh taxed at 30% before applicable adjustments. Health and Education Cess and any applicable surcharge must also be considered. For an illustrative calculation, assume your taxable salary after the standard deduction is ₹39.25 lakh.
| Tax calculation | Amount |
| Annual salary before standard deduction | ₹40,00,000 |
| Standard deduction | ₹75,000 |
| Taxable income | ₹39,25,000 |
| Income tax before cess | ₹7,27,500 |
| Health and Education Cess at 4% | ₹29,100 |
| Illustrative annual income tax | ₹7,56,600 |
This simplified example assumes the entire ₹40 lakh is salary income, excludes employer contributions from the calculation and does not account for any additional salary components or special tax treatment. If your ₹40 lakh figure represents CTC rather than taxable salary, your actual taxable income may be lower. Therefore, this tax calculation should not be treated as a direct prediction of your payslip.
Monthly Salary Deductions on a 40 LPA Package
Besides income tax, other deductions can reduce your monthly take-home pay.
| Deduction | How it affects salary |
| Employee PF | Deducted from eligible salary components and credited to your provident fund |
| Income tax (TDS) | Deducted monthly based on projected annual tax liability |
| Professional tax | State-specific levy, where applicable |
| Employee insurance or other deductions | Depends on the employer’s benefits and payroll policies |
| Variable pay | May be paid separately instead of being included in monthly salary |
Employee Provident Fund (PF)
Employee PF is commonly calculated at 12% of the applicable PF wage, subject to the applicable rules and employer policy. Some employers calculate contributions using the statutory wage ceiling, while others contribute on a higher salary base. For example, a ₹16 lakh annual basic salary would produce an employee PF contribution of ₹1,92,000 annually if the entire basic salary were used as the contribution base. That is ₹16,000 per month deducted from salary. The actual contribution can differ depending on the employer’s PF arrangement.
Professional Tax
Professional tax varies by state and is not applicable everywhere. Where levied, the deduction depends on the relevant state rules and salary category. For example, an employee’s professional tax treatment in Maharashtra may differ from that in Uttar Pradesh. Check the deduction shown in your offer letter or payslip rather than assuming the same amount applies throughout India.
New Tax Regime vs Old Tax Regime for 40 LPA
Choosing the right tax regime can influence your annual tax bill and monthly take-home salary.
| Feature | New tax regime | Old tax regime |
| Tax slab structure | Lower, revised slabs | Existing slab structure |
| Standard deduction | ₹75,000 | ₹50,000 |
| HRA exemption | Generally unavailable | Available if eligible |
| Section 80C deduction | Generally unavailable | Available subject to limits |
| Section 80D deduction | Generally unavailable | Available subject to conditions |
| Best suited for | Employees with fewer eligible deductions | Employees with substantial eligible exemptions and deductions |
The new regime is the default regime, but eligible salaried employees can evaluate the alternative. The better option depends on the total deductions and exemptions you can legitimately claim.
Which Tax Regime Is Better for a ₹40 LPA Salary?
The new tax regime may be more beneficial if you have limited tax-saving investments and do not qualify for significant exemptions. The old regime may be worth comparing if you pay substantial rent, qualify for HRA exemption, have eligible home-loan interest or make qualifying investments.
Do not choose a regime based only on the tax slab rates. Compare the total annual tax liability under both options using your actual salary structure and eligible deductions.
Check Also: 14.5 LPA In Hand Salary in India 2026: Monthly Salary, Tax and PF Breakdown
How to Calculate Your Exact 40 LPA In Hand Salary
To calculate your exact in-hand salary on a ₹40 LPA package, you need to separate your annual CTC into fixed salary, variable pay, employer contributions and other benefits. Then calculate income tax and subtract employee-side deductions from your gross salary.
Follow these steps to estimate your monthly take-home pay.
Step 1: Identify Your Fixed Annual Salary
Check your offer letter to determine how much of the ₹40 lakh CTC is fixed and how much depends on performance. For example, if ₹4 lakh is a performance bonus, your fixed annual CTC is ₹36 lakh. The bonus should not be counted as guaranteed monthly income.
Step 2: Remove Employer Contributions and Non-Cash Benefits
Subtract employer PF contributions, gratuity provisions, insurance benefits, and other components included in your CTC but not paid directly as monthly salary. This gives you a clearer picture of the gross cash salary available before employee deductions.
Step 3: Calculate Your Taxable Income
Determine your taxable salary after accounting for the applicable standard deduction and any other eligible adjustments. Under the new tax regime, salaried employees can generally claim a ₹75,000 standard deduction for FY 2026–27. Your final taxable income depends on your actual salary structure and the applicable tax rules.
Step 4: Calculate Income Tax and Cess
Apply the income tax slabs under your chosen tax regime to calculate your annual tax liability. Add the applicable 4% Health and Education Cess and any surcharge, if applicable. Divide the resulting annual tax by 12 to estimate the monthly TDS deduction, although actual payroll deductions may vary.
Step 5: Subtract Employee-Side Deductions
Deduct employee PF, professional tax where applicable, and any other payroll deductions from your monthly gross salary after accounting for income tax. The remaining amount is your estimated monthly in-hand salary.
Formula:
Monthly in-hand salary = (Annual gross cash salary − annual income tax − annual employee deductions) ÷ 12
For example, if your annual gross cash salary is ₹37 lakh, your annual income tax is ₹7 lakh, and your annual employee-side deductions total ₹1.92 lakh, your estimated monthly take-home salary would be approximately ₹2,34,000. This is an illustrative calculation, not a universal estimate for every ₹40 LPA package. Your actual in-hand salary will depend on your fixed pay, taxable components, PF arrangement, tax regime, and bonus structure.
Is 40 LPA a Good Salary in India?
Yes, ₹40 LPA is a high annual compensation package in India. It can provide considerable financial flexibility, although the lifestyle it supports depends on where you live, your household expenses and your financial commitments.
In cities such as Bengaluru, Mumbai, Hyderabad and Delhi NCR, housing and lifestyle costs can consume a substantial share of take-home pay. In smaller cities, the same income may provide greater purchasing power.
A monthly take-home salary of ₹2.35 lakh, for example, could support rent, household expenses, insurance, investments, travel and other financial goals. The important consideration is how much remains after essential expenses rather than the headline CTC alone.
How Much Can You Save on a 40 LPA Salary?
Your savings depend on your spending habits and financial responsibilities. Consider this illustrative monthly budget based on a take-home salary of ₹2.35 lakh.
| Expense or goal | Monthly allocation |
| Rent and household expenses | ₹50,000 |
| Food and groceries | ₹15,000 |
| Transport | ₹12,000 |
| Insurance and medical expenses | ₹8,000 |
| Shopping and entertainment | ₹20,000 |
| Travel fund | ₹15,000 |
| Total expenses and allocations | ₹1,20,000 |
| Potential monthly savings | ₹1,15,000 |
This is only a sample budget. Actual expenses will vary, and the travel allocation is a planned expense rather than a saving. You can direct the remaining amount toward an emergency fund, retirement investments, a home purchase or other long-term goals.
Check Also: 13.5 LPA In Hand Salary: How Much Will You Actually Get Every Month in 2026?
Factors That Can Change Your Monthly Take-Home Salary
Before accepting a ₹40 lakh offer, review these factors carefully:
- Fixed versus variable pay: A package containing a large performance bonus may provide a lower guaranteed monthly salary.
- Employer PF: A higher employer contribution can form part of your CTC without reaching your bank account.
- Gratuity: The provision may be included in CTC but is not normally paid as monthly salary.
- Tax regime: Eligible deductions and exemptions can change the final tax liability.
- Location: Professional tax and certain payroll arrangements vary by state.
- Stock compensation: ESOPs and other equity benefits should not be treated as guaranteed monthly cash income.
Request a detailed salary breakup from HR before comparing offers. A package with a slightly lower headline CTC but a higher fixed cash component may provide more predictable monthly income.
Final Verdict
A ₹40 lakh annual CTC can translate into approximately ₹2.3 lakh to ₹2.4 lakh in monthly take-home pay, but there is no single in-hand figure applicable to every employee. Income tax, PF contributions, gratuity, variable pay and the salary structure all influence the final amount. Before accepting an offer, check the fixed annual gross salary, guaranteed monthly pay and employer contributions separately. Comparing both tax regimes and calculating your expected bank credit will give you a clearer picture of what a 40 LPA package actually means for your finances.
Use Our Free Tool
Frequently Asked Questions
The estimated monthly take-home salary on a ₹40 lakh CTC package is around ₹2.28 lakh to ₹2.45 lakh under common salary structures. The exact amount depends on income tax, PF, variable pay, and employer benefits.
A ₹40 lakh CTC may result in approximately ₹27 lakh to ₹29 lakh in annual take-home pay under typical assumptions. Your actual annual net salary depends on the CTC breakup and applicable deductions.
Income tax depends on taxable income and the chosen tax regime. Employer PF, gratuity, the standard deduction and other eligible adjustments can affect the final calculation.
Yes. It is a high compensation package that can support a comfortable lifestyle and substantial savings. Your purchasing power will depend on your city, housing costs, family commitments, and spending habits.
The new regime may suit employees with fewer eligible deductions, while the old regime can be competitive for those with substantial exemptions and deductions. Compare both using your actual salary details before making a decision.

Hi, I’m Kashish Arora, an SEO specialist and finance content researcher passionate about simplifying salary and compensation topics. I create well-researched content on CTC, in-hand salary, salary structure, pay scales, salary slips, tax calculations, EPF, gratuity, bonuses, deductions, and employee benefits.
My articles are based on official government guidelines, employer policies, tax regulations, and other reliable public sources. I aim to explain complex payroll and taxation concepts in simple language so that employees, job seekers, HR professionals, and students can easily understand how salaries are calculated and how deductions affect take-home pay.
Along with payroll and taxation topics, I also cover salary insights for government employees, private-sector professionals, executives, and public personalities whenever reliable information is available.