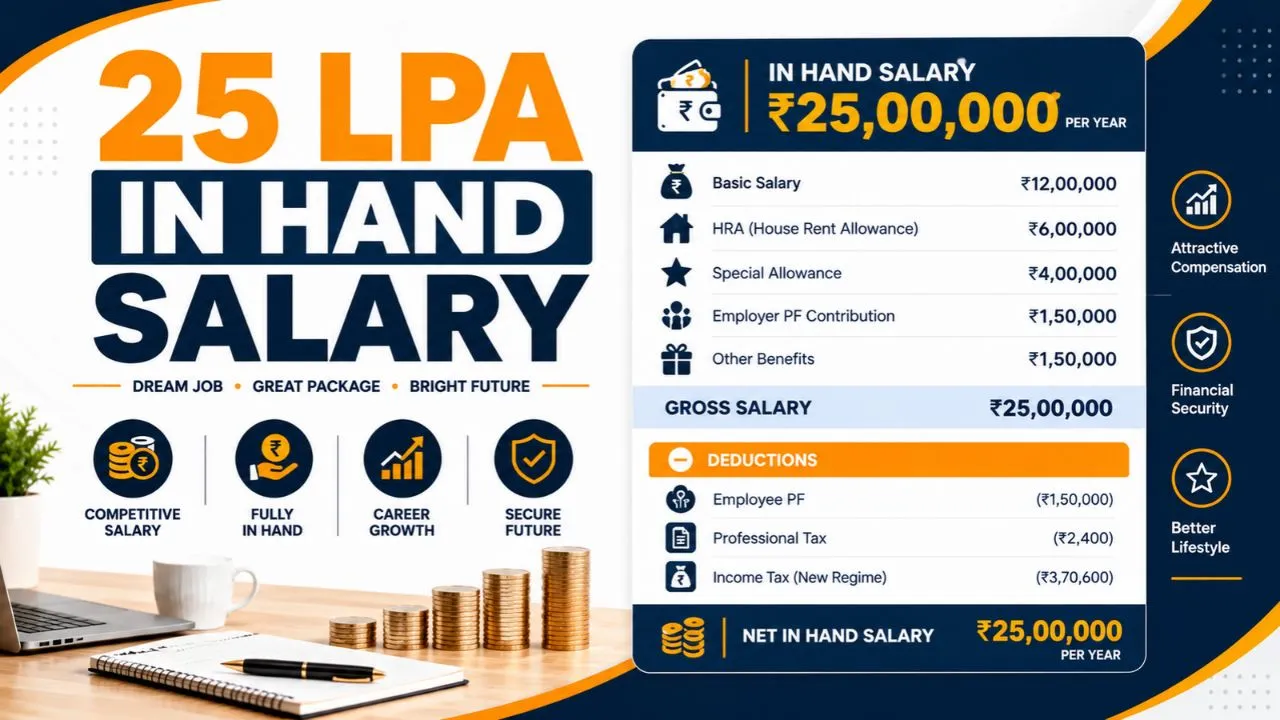

A salary package of ₹25 LPA means an annual Cost to Company (CTC) of ₹25,00,000. However, the amount credited to your bank account will be lower because CTC may include employer PF contributions, gratuity, and performance bonuses, along with deductions for income tax, employee PF and professional tax.
The 25 LPA in hand salary per month is approximately ₹1.56 lakh to ₹1.69 lakh under several FY 2026–27 salary calculator assumptions. The exact amount depends on your salary structure, tax regime and employer’s payroll policies.
25 LPA In Hand Salary Per Month
For a ₹25 lakh annual CTC, the monthly salary before deductions is ₹2,08,333. The actual take-home salary is generally lower because not every component of CTC is paid as monthly cash.
| Salary Details | Estimated Amount |
|---|---|
| Annual CTC | ₹25,00,000 |
| Monthly CTC | ₹2,08,333 |
| Estimated monthly in-hand salary | ₹1,56,000–₹1,69,000 |
| Estimated annual take-home | ₹18.73 lakh–₹20.28 lakh |
| Tax regime | New regime, FY 2026–27 |
The range reflects different published calculator assumptions, not a guaranteed salary band. For example, Flexiple estimates a monthly take-home of ₹1,64,183 under its default new-regime calculation, while SalaryInHand estimates ₹1,56,134 using a different salary structure.
25 LPA Salary Breakup
A typical ₹25 LPA package can include basic salary, House Rent Allowance (HRA), special allowance and employer contributions. The following is an illustrative salary structure for an employee whose employer PF contribution is included in CTC.
| Salary Component | Annual Amount | Monthly Equivalent |
|---|---|---|
| Basic salary | ₹10,00,000 | ₹83,333 |
| House Rent Allowance (HRA) | ₹5,00,000 | ₹41,667 |
| Special allowance | ₹8,80,000 | ₹73,333 |
| Employer PF contribution | ₹1,20,000 | ₹10,000 |
| Total CTC | ₹25,00,000 | ₹2,08,333 |
Illustrative structure based on basic salary at 40% of CTC. Actual components vary by employer. Figures are rounded. In this example, the employer’s PF contribution is part of the total package but is not added to the employee’s monthly bank credit. The employee’s own PF contribution is deducted separately from salary.
Some employers also include gratuity, health insurance, annual bonuses or other benefits in CTC. If these components are included, the regular monthly cash salary can be lower than the amount suggested by dividing CTC by 12.
₹25 LPA Fixed Salary vs ₹25 LPA CTC
A ₹25 LPA CTC package and a ₹25 lakh fixed salary do not necessarily result in the same monthly take-home pay. The difference depends on whether the package includes employer contributions, insurance, gratuity and variable compensation.
| Feature | ₹25 LPA CTC Package | ₹25 LPA Fixed Cash Salary |
|---|---|---|
| Annual package | ₹25,00,000 | ₹25,00,000 fixed compensation |
| Employer PF | May be included in CTC | Depends on the offer structure |
| Gratuity and insurance | May be included | Depends on the offer structure |
| Variable bonus | May be included in the package | May be separate or absent |
| Monthly cash salary | Depends on the salary breakup | Depends on payroll components and deductions |
| Take-home pay | Can be lower if CTC includes non-cash components | Can be higher if more of the package is fixed cash, but not guaranteed |
Example: If a ₹25 lakh CTC includes ₹1.2 lakh in employer PF and ₹50,000 in insurance and other benefits, the amount remaining for other salary components is lower than ₹25 lakh. The actual bank credit will also depend on income tax, employee PF and other payroll deductions. When comparing job offers, check the annual fixed gross salary, variable pay, employer PF, gratuity and estimated monthly deductions separately.
Deductions from a 25 LPA Salary
Three deductions commonly affect the monthly take-home salary.
1. Income Tax
Income tax is calculated on taxable salary rather than simply applying a flat percentage to the full CTC. Under the new tax regime, eligible salaried employees can claim the applicable standard deduction of ₹75,000 for the calculation shown here.
The applicable new-regime tax slabs for FY 2026–27 are:
| Taxable Income Slab | Tax Rate |
|---|---|
| Up to ₹4,00,000 | Nil |
| ₹4,00,001–₹8,00,000 | 5% |
| ₹8,00,001–₹12,00,000 | 10% |
| ₹12,00,001–₹16,00,000 | 15% |
| ₹16,00,001–₹20,00,000 | 20% |
| ₹20,00,001–₹24,00,000 | 25% |
| Above ₹24,00,000 | 30% |
Health and Education Cess is also applicable.
2. Employee Provident Fund (PF)
Employee PF is a retirement saving contribution deducted from salary. A common calculation uses 12% of basic salary, although the applicable contribution base and employer’s PF policy can differ.
For the illustrative salary structure above:
- Annual basic salary: ₹10,00,000
- Employee PF at 12% of basic: ₹1,20,000 per year
- Monthly employee PF: ₹10,000
This deduction reduces the monthly amount credited to your bank account, but the contribution goes towards your retirement savings.
3. Professional Tax
Professional tax is a state-level levy that applies according to the relevant state’s rules. Where applicable, it is deducted from salary by the employer.
Some salary calculators use ₹200 per month as an assumption, while the actual amount can differ by state and applicable rules. Other payroll deductions, such as insurance premiums or meal benefits, may also affect take-home pay.
25 LPA In Hand Salary Calculation: Worked Example
Here is a worked example using Flexiple’s published assumptions for a ₹25 LPA CTC under the new tax regime.
| Calculation | Annual Amount |
|---|---|
| Total CTC | ₹25,00,000 |
| Less: Employer PF included in CTC | −₹1,20,000 |
| Gross salary for this example | ₹23,80,000 |
| Less: Standard deduction | −₹75,000 |
| Taxable salary | ₹23,05,000 |
| Estimated income tax, including cess | −₹2,87,300 |
| Employee PF contribution | −₹1,20,000 |
| Assumed professional tax | −₹2,500 |
| Estimated annual in-hand salary | ₹19,70,200 |
| Estimated monthly in-hand salary | ₹1,64,183 |
This example assumes no variable pay and uses the stated PF and professional tax assumptions. The standard deduction reduces taxable income; it is not an additional cash deduction from the salary credited to your account.
Your actual in-hand salary may differ if your company uses a different basic salary percentage, includes gratuity or insurance in CTC, pays part of the package as a bonus, or calculates PF differently.
Note: Before publishing, reconcile the illustrative tax figure with the applicable FY 2026–27 tax computation and the employee’s actual taxable salary.
₹25 LPA Salary Slip Example
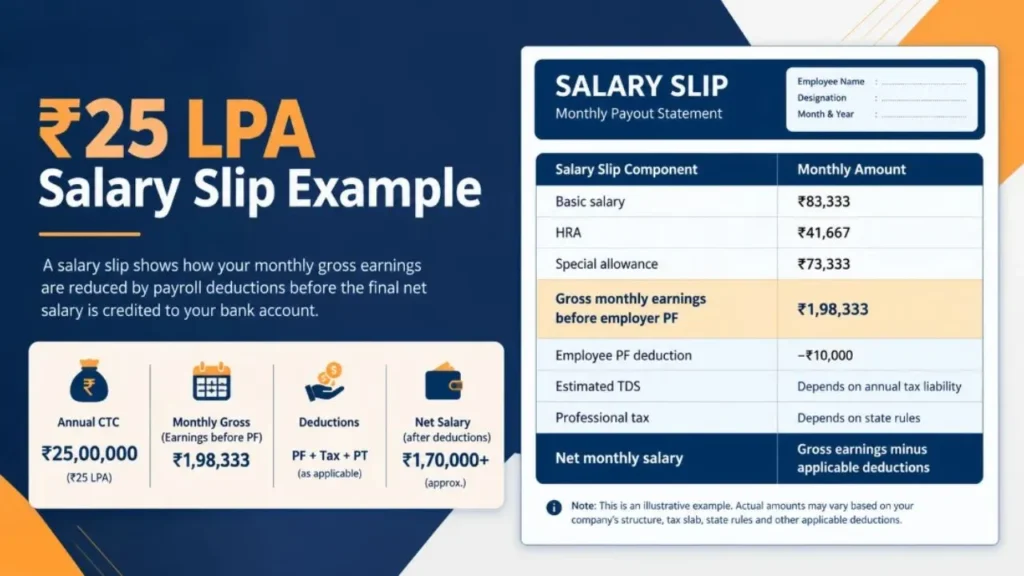
A salary slip shows how your monthly gross earnings are reduced by payroll deductions before the final net salary is credited to your bank account. The following is an illustrative monthly format based on the salary structure used earlier.
| Salary Slip Component | Monthly Amount |
|---|---|
| Basic salary | ₹83,333 |
| HRA | ₹41,667 |
| Special allowance | ₹73,333 |
| Gross monthly earnings before employer PF | ₹1,98,333 |
| Employee PF deduction | −₹10,000 |
| Estimated TDS | Depends on annual tax liability |
| Professional tax | Depends on state rules |
| Net monthly salary | Gross earnings minus applicable deductions |
This example excludes employer PF from cash earnings because it is included separately in CTC. The exact salary slip will vary by employer, and TDS may change when bonuses or other taxable payments are included.
Old Tax Regime vs New Tax Regime for 25 LPA
The tax regime you choose can influence the amount of salary you take home. The new regime generally offers lower slab rates with fewer deductions, while the old regime permits eligible deductions and exemptions, subject to their respective rules.
| Feature | New Tax Regime | Old Tax Regime |
|---|---|---|
| Standard deduction | ₹75,000 under the assumptions used here | ₹50,000 under the assumptions used here |
| Section 80C deduction | Generally unavailable | Available subject to conditions and limits |
| HRA exemption | Generally unavailable | Available subject to eligibility |
| Section 80D deduction | Generally unavailable | Available subject to eligibility |
| Tax-saving paperwork | Usually simpler | More documentation may be required |
| Best choice | Depends on income and salary structure | Depends on eligible exemptions and deductions |
The standard deduction amounts shown above are based on the applicable provisions for the example; verify the rules for the relevant tax year before filing your return. For a practical comparison, Flexiple estimates ₹1,64,183 per month under the new regime and ₹1,52,180 under the old regime with its specified assumptions. This is not a universal result: eligible HRA, investments, insurance premiums and other deductions can change which regime is more beneficial. Compare both regimes using your actual salary components and eligible deductions rather than selecting one solely on the basis of the CTC. Source: incometaxindia.gov.in
₹20 LPA vs ₹25 LPA vs ₹30 LPA In-Hand Salary
Comparing different salary packages can help you understand how a higher CTC may affect your monthly income. The following table shows the monthly equivalent of each annual package before deductions.
| Annual CTC | Monthly CTC Equivalent | Actual In-Hand Salary |
|---|---|---|
| ₹20 LPA | ₹1,66,667 | Depends on tax, PF and salary structure |
| ₹25 LPA | ₹2,08,333 | Depends on tax, PF and salary structure |
| ₹30 LPA | ₹2,50,000 | Depends on tax, PF and salary structure |
These figures represent CTC divided by 12, not the actual monthly bank credit. A higher CTC can also include a larger variable bonus, employer contributions or benefits that are not paid as monthly cash.
For a meaningful comparison, use the same assumptions for all three packages, including the basic salary percentage, PF calculation, tax regime and variable compensation.
Does Variable Pay Affect 25 LPA In-Hand Salary?
Yes. A ₹25 LPA package does not necessarily mean you will receive ₹2,08,333 as gross monthly salary. For example, an offer might include ₹22 lakh in fixed CTC and ₹3 lakh in performance-linked compensation. The bonus may be paid quarterly or annually, depending on company policy and performance conditions. In that case, your regular monthly salary is based on the fixed-pay structure, while the bonus is credited separately when it becomes payable. Tax withholding may also vary in months when bonuses are paid.
Before accepting an offer, check the offer letter for:
- Fixed annual salary
- Variable pay and bonus conditions
- Employer and employee PF contributions
- Gratuity and insurance components
- Joining or retention bonuses
- Monthly gross salary and estimated deductions
This breakdown gives you a more realistic picture of your regular monthly income.
₹25 LPA In-Hand Salary in Different Indian Cities
The take-home salary from a ₹25 LPA package depends mainly on the salary structure and tax deductions, but your potential savings also depend on where you live.
| City | Expense Factors to Consider |
|---|---|
| Mumbai | Rent, commuting and housing costs |
| Bengaluru | Rent near technology hubs, transport and food |
| Gurugram | Rent, commuting and lifestyle expenses |
| Hyderabad | Housing, transport and household costs |
| Pune | Rent, commuting and daily expenses |
| Noida | Rent, transport and family expenses |
Your post-tax salary may be similar across these cities if your salary structure and tax circumstances are the same. However, rent and other living costs can significantly change the amount left for savings.
Use local rental prices and your actual monthly expenses to compare potential savings rather than assuming that a higher salary automatically provides the same lifestyle in every city.
Is 25 LPA a Good Salary in India?
Yes, ₹25 LPA can provide a comfortable standard of living for many professionals in India. An estimated monthly take-home of around ₹1.6 lakh gives considerable scope for housing, household expenses, insurance, travel and investments. However, the lifestyle it supports depends on where you live and your financial responsibilities. Rent in Bengaluru, Mumbai or Gurugram can consume a substantially larger share of income than housing in many smaller cities.
A simple monthly budget based on ₹1,60,000 in-hand salary might look like this:
| Expense Category | Illustrative Monthly Budget |
|---|---|
| Rent and maintenance | ₹30,000 |
| Food and groceries | ₹15,000 |
| Transport | ₹8,000 |
| Utilities and phone | ₹5,000 |
| Family and personal expenses | ₹17,000 |
| Insurance and medical costs | ₹5,000 |
| Entertainment and travel fund | ₹10,000 |
| Total planned expenses | ₹90,000 |
| Potential savings and investments | ₹70,000 |
This is an illustrative budget, not a national spending average. Actual expenses depend on rent, family size, loans and lifestyle.
A person with fewer financial obligations may save more, while someone supporting family members or repaying a home loan may have less available for investment.
How to Increase Your Take-Home Salary
Although you cannot eliminate mandatory taxes and deductions, you can make informed decisions about your compensation. Compare fixed and variable pay: A higher fixed component can provide more predictable monthly income than a package heavily dependent on annual incentives. Compare both tax regimes: Calculate the tax liability under each regime using your actual eligible deductions and exemptions.
Understand your PF structure: Ask HR how employee and employer PF are calculated and whether employer PF is included in CTC. Review benefits and reimbursements: Understand which benefits are taxable, which are exempt under applicable rules, and which do not form part of monthly cash pay.
Use a salary calculator: Enter your actual CTC, state, basic salary, variable pay and deductions to obtain a more personalised estimate. The goal should be to understand your complete compensation package, not just the headline LPA figure.
How to Calculate Your Exact 25 LPA In-Hand Salary
To estimate your actual monthly take-home, collect the following information from your offer letter or HR department:
- Total annual CTC and fixed annual salary.
- Basic salary and HRA.
- Employer PF contribution and employee PF deduction.
- Gratuity, insurance and other benefits included in CTC.
- Variable pay, bonus and payment schedule.
- Applicable tax regime and other eligible deductions.
- Professional tax and any additional payroll deductions.
First, separate monthly cash earnings from benefits and employer contributions. Then calculate taxable salary under the applicable tax rules, estimate annual tax, and subtract employee PF, professional tax and other deductions from cash earnings.
Finally, divide the expected annual take-home by 12 to estimate the monthly average. Actual bank credits can vary because of bonuses, tax adjustments, unpaid leave and other payroll changes.
Conclusion
A ₹25 LPA package translates to ₹2,08,333 per month in annualised CTC, but the actual 25 LPA in hand salary per month can be considerably lower. Published FY 2026–27 calculations place the monthly take-home at roughly ₹1.56 lakh to ₹1.69 lakh under different assumptions. To determine your actual salary, review your fixed pay, variable compensation, PF contributions, gratuity and tax regime. A calculation based on your offer letter will provide a more reliable estimate than the headline CTC alone.
USE OUR FREE TOOLS
Frequently Asked Questions
The estimated monthly take-home is approximately ₹1.56 lakh to ₹1.69 lakh under different published FY 2026–27 calculator assumptions. Your actual salary depends on tax, PF, variable pay and the structure of your CTC.
₹25,00,000 divided by 12 equals approximately ₹2,08,333 per month. This is the monthly equivalent of annual CTC, not necessarily your gross monthly salary or bank credit.
It depends on taxable salary and the applicable tax regime. In Flexiple’s example, the estimated annual income tax, including cess, is ₹2,87,300 under the new regime.
It can be better for employees who do not claim substantial eligible deductions under the old regime. However, the result depends on your HRA eligibility, investments, insurance premiums and other applicable tax benefits.
The ₹25 LPA CTC may include employer PF, gratuity, insurance and variable compensation that is not paid as regular monthly cash. Income tax, employee PF and applicable professional tax further reduce the amount credited to your bank account.
No. CTC may include employer PF, gratuity, insurance and variable pay. Fixed salary refers to the guaranteed compensation defined in the offer, although its exact components depend on the employer’s salary structure.
Savings depend on actual take-home pay and expenses. For example, if your monthly in-hand salary is ₹1,60,000 and your total monthly expenses are ₹90,000, you could potentially save ₹70,000 per month.
It can. Some employers include performance bonuses, gratuity, and insurance in CTC, while others show certain components separately. Check the offer letter to understand what is included.
Separate fixed cash earnings from employer contributions and benefits, estimate income tax under your selected regime, and subtract employee PF, professional tax, and other payroll deductions. Your employer’s salary breakup and tax calculation will determine the final amount.

Hi, I’m Kashish Arora, an SEO specialist and finance content researcher passionate about simplifying salary and compensation topics. I create well-researched content on CTC, in-hand salary, salary structure, pay scales, salary slips, tax calculations, EPF, gratuity, bonuses, deductions, and employee benefits.
My articles are based on official government guidelines, employer policies, tax regulations, and other reliable public sources. I aim to explain complex payroll and taxation concepts in simple language so that employees, job seekers, HR professionals, and students can easily understand how salaries are calculated and how deductions affect take-home pay.
Along with payroll and taxation topics, I also cover salary insights for government employees, private-sector professionals, executives, and public personalities whenever reliable information is available.
Leave a Reply